
SBA loan website designCompare every mortgage website design →
Bring in owner-user deals, not shopping calls
SBA 504, 7(a) and owner-occupied debt explained for business owners, with a deal form your referral partners can use.
- Pages
- 32
- Screens below
- 6
- Status
- Live
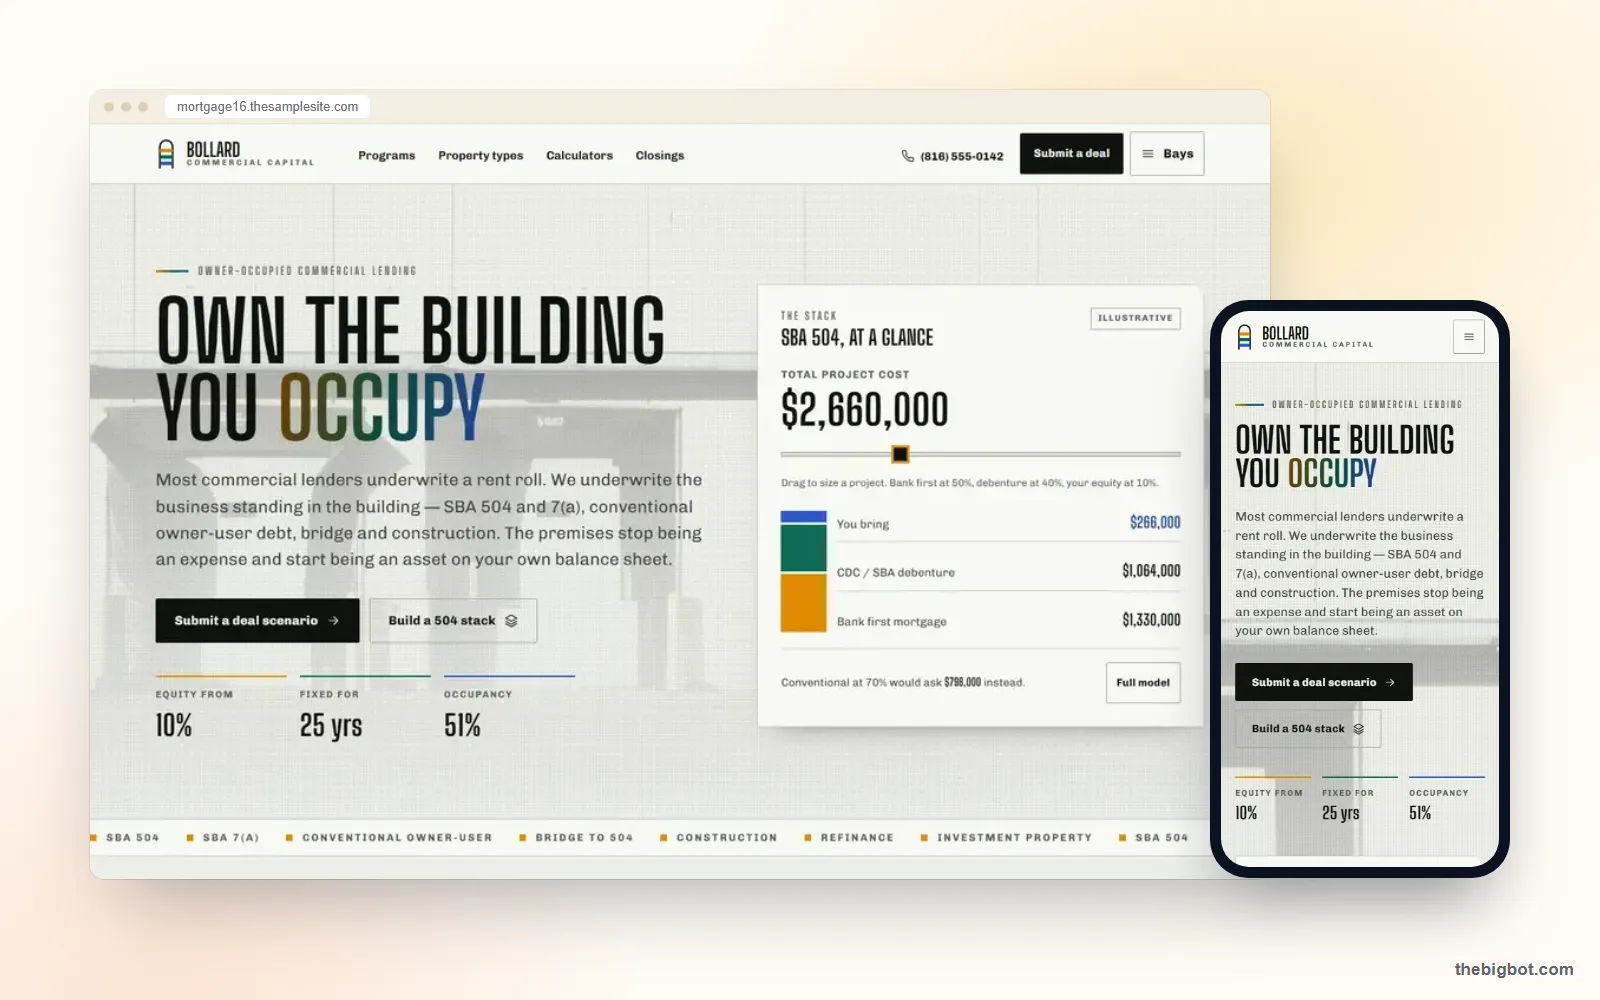
Every screen of Bollard
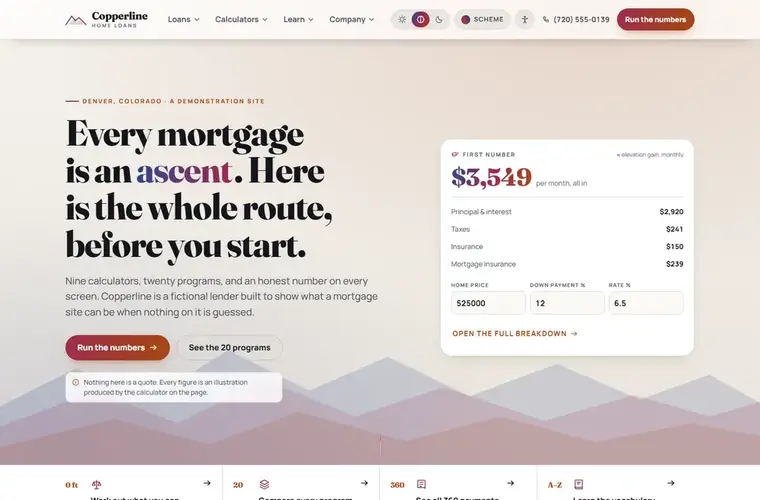
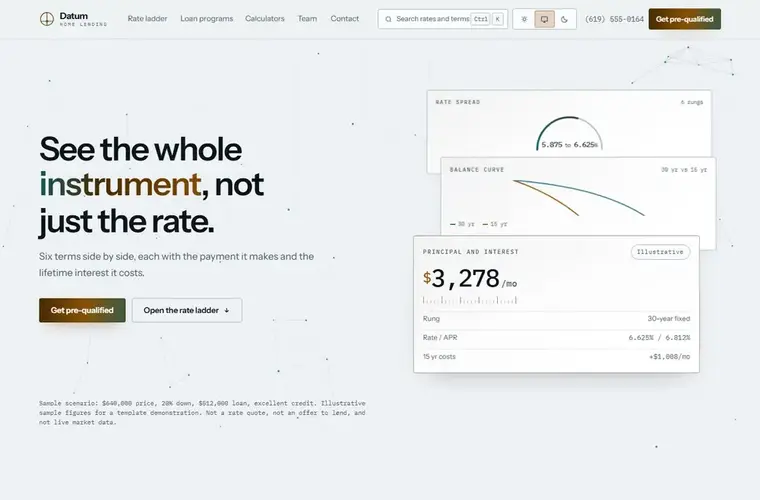
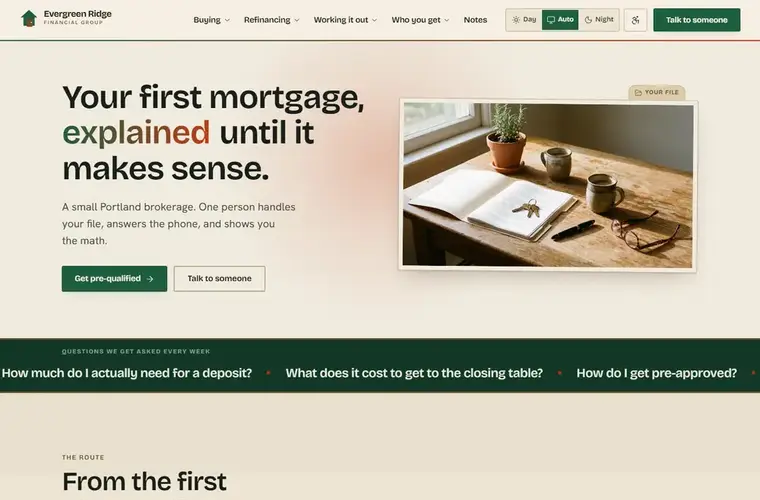
Captured from the live Bollard Commercial Capital demo: home, the program pages, insights, about and contact.

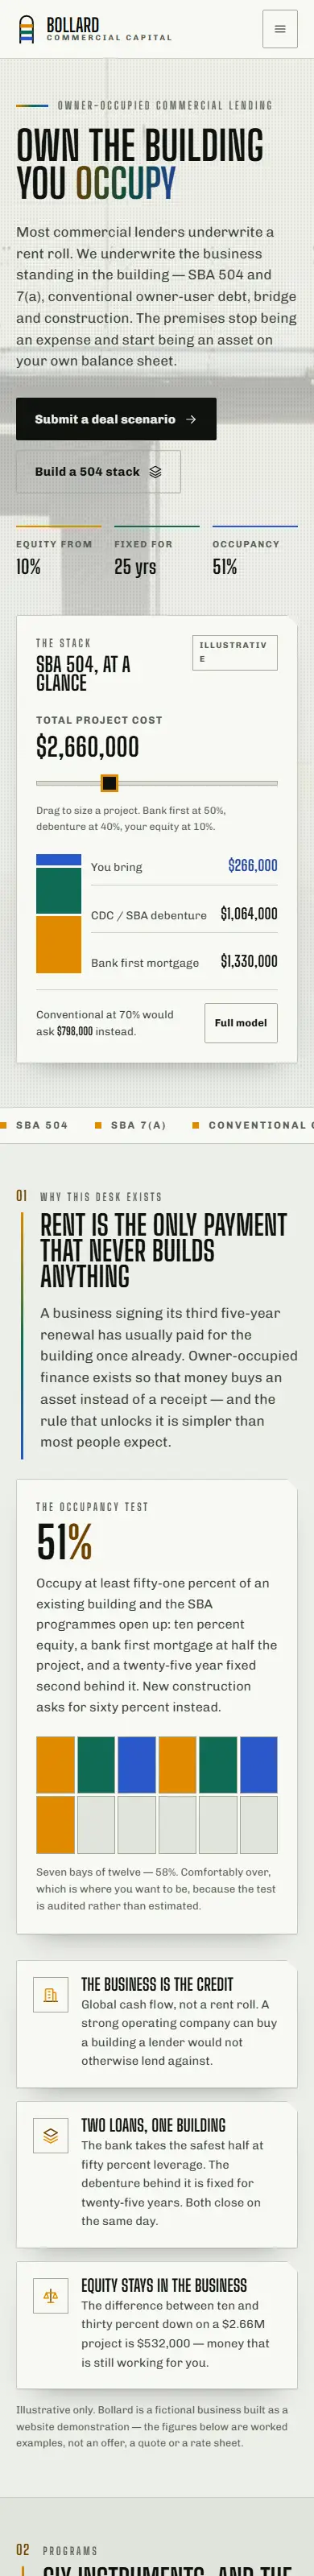


Where Bollard wins
Bollard suits a lender or broker who helps business owners buy the property they operate from. It explains SBA 504 and 7(a) alongside conventional owner-user, bridge and construction debt, with a deal submission path for brokers.
SBA and owner-user commercial lendersWritten for the occupier, not the investor
The whole site argues for owning the building you work in, which is a different conversation from yield.
A deal desk, not a contact form
The submit-a-deal path collects property, loan and occupancy details, so the first reply can be useful.
The closing laid out in advance
A step-by-step timeline sets expectations on a process most first-time commercial borrowers find opaque.
Also on the site
SBA 504 and 7(a). Program pages for the two main SBA real estate loans.
Six commercial calculators. Owner-occupied models with the math shown.
Submit a deal. A deal scenario form for business owners and referring brokers.
Closing process. A step-by-step closing timeline and illustrative closings.
SBA 504 and 7(a), the way a business owner needs them explained
Owner-users compare these two programs before they compare lenders. These are the points Bollard’s program pages make, taken from SBA’s own descriptions.
504 is for fixed assets
SBA 504 loans provide long-term, fixed-rate financing for major fixed assets such as an owner-occupied building or long-life equipment.
A three-part structure
A typical 504 project combines a bank loan, a second loan through a Certified Development Company and an equity contribution from the business.
7(a) is the general program
7(a) loans can cover real estate, working capital and business acquisitions. SBA lists the maximum 7(a) loan as $5 million.
Occupancy matters
These programs serve businesses buying property they will operate from. A building bought mainly to lease to others is an investment loan, not an owner-user one.
Sources: SBA 504 loans, SBA 7(a) loans.
Rebuilding Bollard as your site
Bollard is written for business owners buying their own premises, so the rebuild keeps that occupier voice and adds your lending details.
- SBA pages set to your role. The 504 and 7(a) pages are adjusted for whether you lend directly, partner with a Certified Development Company or package deals as a broker.
- Deal form fields agreed. The submit-a-deal form collects the property, loan and occupancy details you need for a first answer.
- Closing timeline in your steps. The step-by-step closing timeline is rewritten to match your actual process.
Pick Bollard if
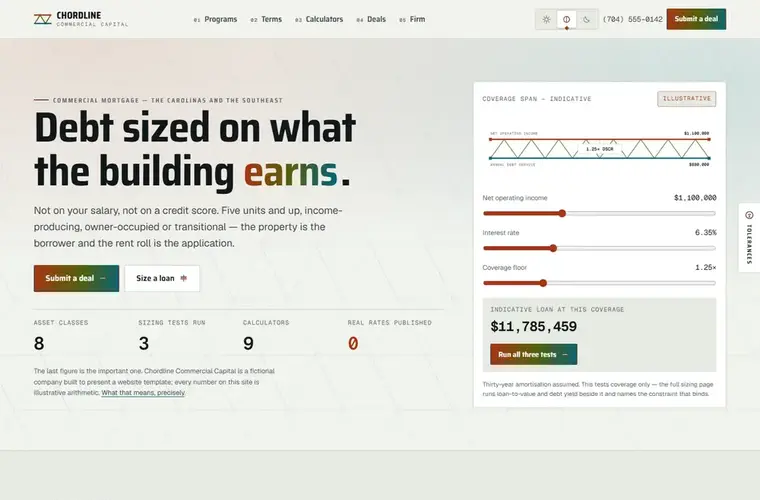
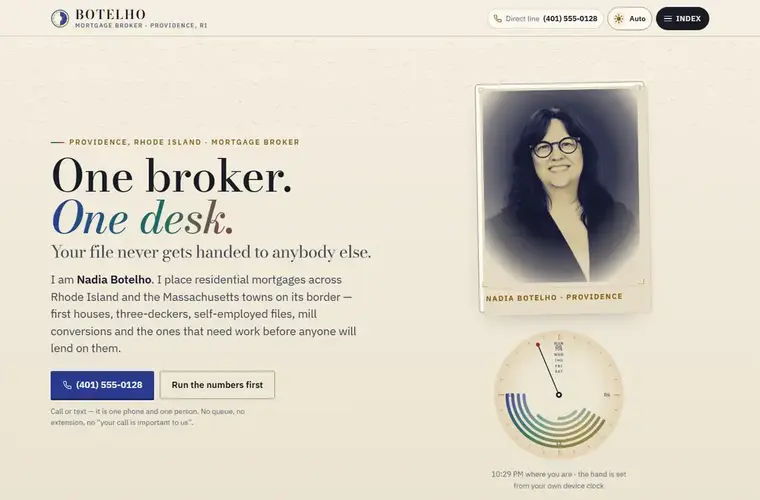
If not, Chordline or Botelho may suit you better.
- You finance business owners buying their own premises
- SBA 504 and 7(a) are a real part of your book
- Referring brokers need somewhere to send a deal
Questions about Bollard
Who is the Bollard design for?+
Does Bollard include a deal submission form?+
What is the difference between SBA 504 and 7(a)?+
Is Bollard for investors buying rental property?+
Launch Bollard as your website.
An owner-user lending site with a real deal desk, on your own domain.
Book a Demo →