
Mortgage website with calculatorsAll live mortgage lender website designs →
Let borrowers see the payment before they call you
Nine calculators and twenty program pages answer the money question first, so the lead that reaches you already trusts the number.
- Pages
- 81
- Screens below
- 6
- Status
- Live
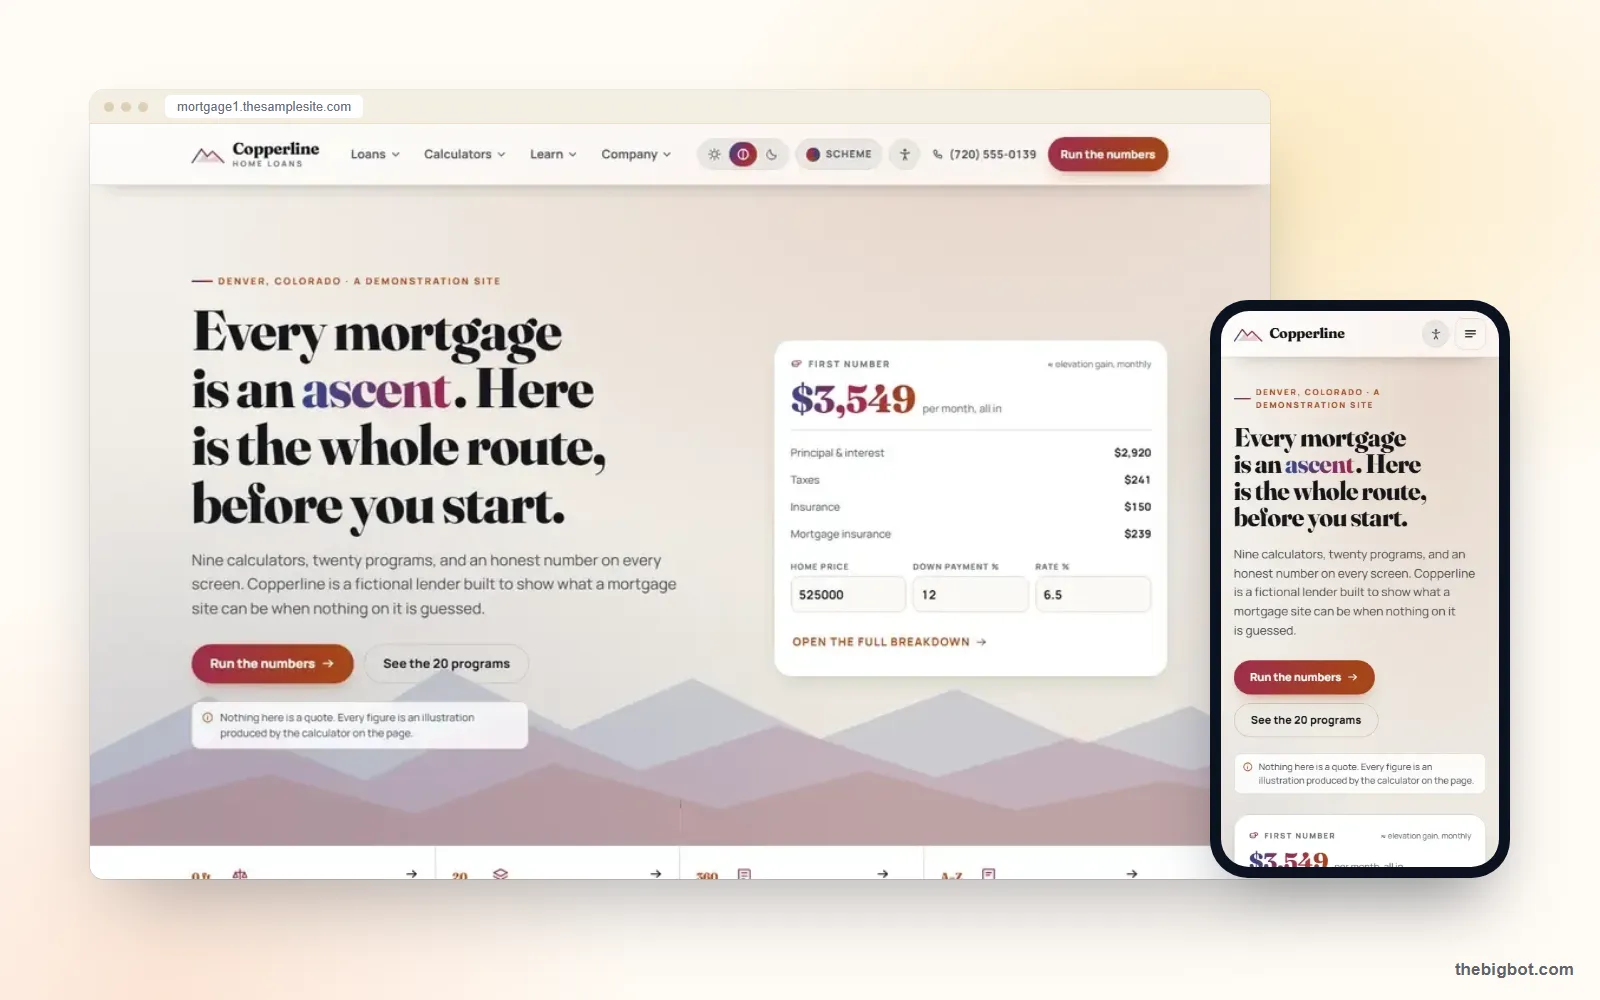
Every screen of Copperline
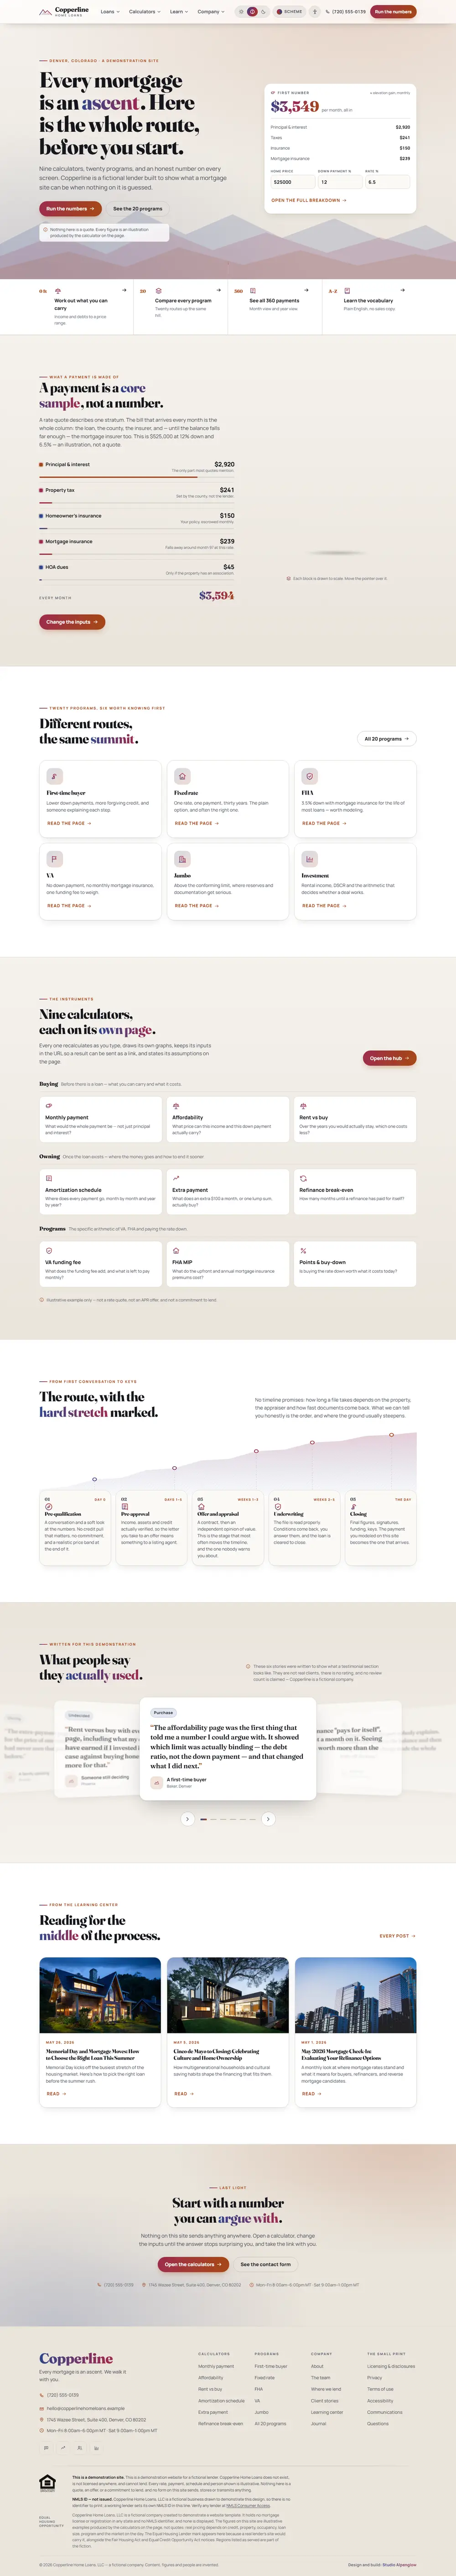
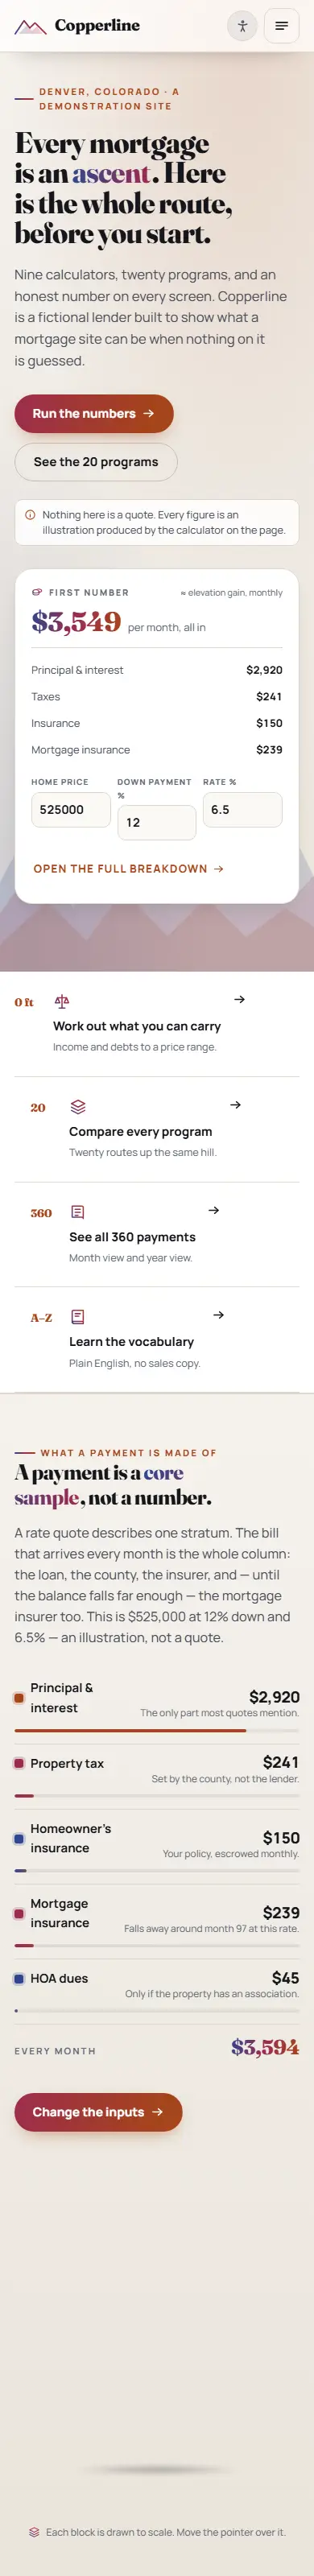
Captured from the live Copperline Home Loans demo: the home page with its payment breakdown, the loan options library, the learning center and a phone view.


Where Copperline wins
Copperline suits a loan officer or small lender whose borrowers want to run the numbers before they call. Every program page links to a calculator, and every calculator shows the full monthly payment, not just principal and interest.
Loan officers who win on payment clarityThe number is on the first screen
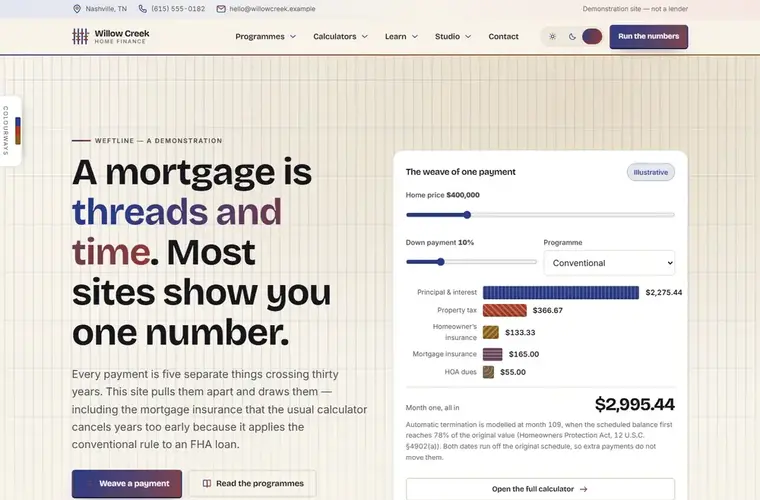
The hero carries a live payment breakdown with principal, taxes, insurance and mortgage insurance split out, so a visitor sees the honest figure before they scroll.
Every calculator is a page
Nine calculators sit on their own URLs, which means nine more entry points from search instead of one calculator buried in a tab.
A rate is never claimed
Figures are labeled as illustrations produced by the calculator, so the site never reads as a quote and your compliance lead has less to argue with.
Also on the site
Nine calculators. Payment, affordability, amortization and refinance tools, each with results a borrower can share.
Twenty program pages. Fixed, FHA, VA, jumbo, investment and more, each written as its own page for search.
Five color schemes. Switchable palettes drawn for light and dark mode, so the site can match your brand.
Illustrative figures labeled. Every example number is marked as an illustration, which keeps the copy compliance-friendly.
What a mortgage payment calculator has to show
A calculator that shows principal and interest alone understates the payment. These are the lines Copperline itemizes, and the rules behind them.
Taxes and insurance
Principal, interest, property tax and homeowners insurance together make up the payment most borrowers actually pay through escrow. Leave the last two out and your number looks lower than the Loan Estimate will.
Mortgage insurance and when it ends
On a conventional loan a borrower can ask to cancel private mortgage insurance at 80% of the original value, and it ends automatically at 78% on the original schedule. FHA premiums follow their own rules.
HOA dues
Condo and planned-community buyers need dues in the monthly figure, or the affordability answer is wrong by exactly that amount.
Trigger-term wording
If a page states a payment amount, down payment or term, Regulation Z requires the APR and repayment terms alongside it. Copperline labels every example as an illustration for that reason.
A result that can be shared
A link that reopens the same inputs lets a borrower send the number to a partner or an agent without a screenshot.
Sources: Homeowners Protection Act, 12 U.S.C. 4902, Regulation Z § 1026.24 (advertising).
Rebuilding Copperline as your site
Copperline launches with your assumptions, not ours. Most of the work sits in the calculators and the twenty program pages, because those are what borrowers share.
- Calculators set to your defaults. Property tax rate, homeowners insurance estimate, mortgage insurance factors and default down payment are set for your market, so the first number a visitor sees is close to what you would quote.
- Program pages trimmed to what you place. Of the twenty program pages, the ones you do not offer come out and the rest get your overlays, minimum scores and document lists.
- Illustration labels kept. Every calculator result keeps its illustration label and gains your NMLS number and the APR wording your compliance lead approves.
Pick Copperline if
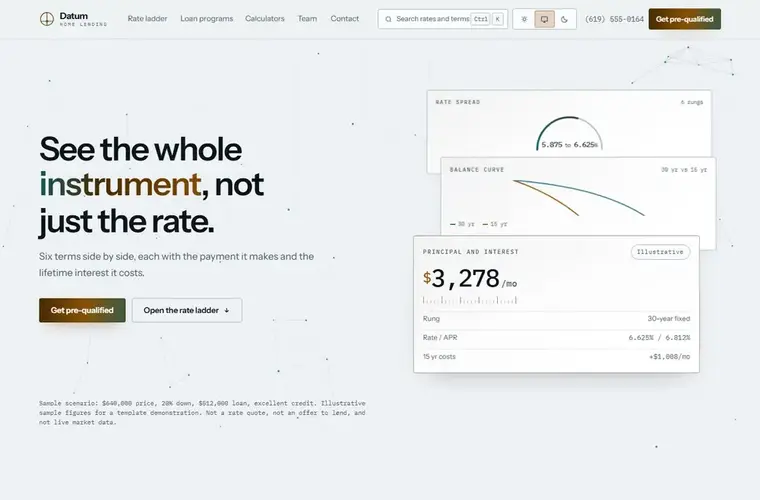
If not, Datum or Throughline may suit you better.
- Your borrowers ask "what would my payment be?" before they ask anything else
- You want twenty program pages doing the ranking work, not one page listing everything
- You send payment breakdowns by text and want a link that opens the same numbers
Questions about Copperline
Do the calculators on Copperline actually work?+
Can Copperline show my own loan programs?+
Which calculators does Copperline include?+
Can I change the default tax and insurance figures?+
Launch Copperline as your website.
Your programs, your calculator defaults and your NMLS number, on your own domain.
Book a Demo →