
Loan officer website designAll live mortgage lender website designs →
Loan officer website design one person can keep current
Good loan officer website design puts your NMLS ID and licensed states on every page, keeps rate and payment wording within Regulation Z, captures leads with a short pre-qual form and calendar, and loads fast on a phone. Throughline does all of that in 24 pages.
- Pages
- 24
- Screens below
- 6
- Status
- Live
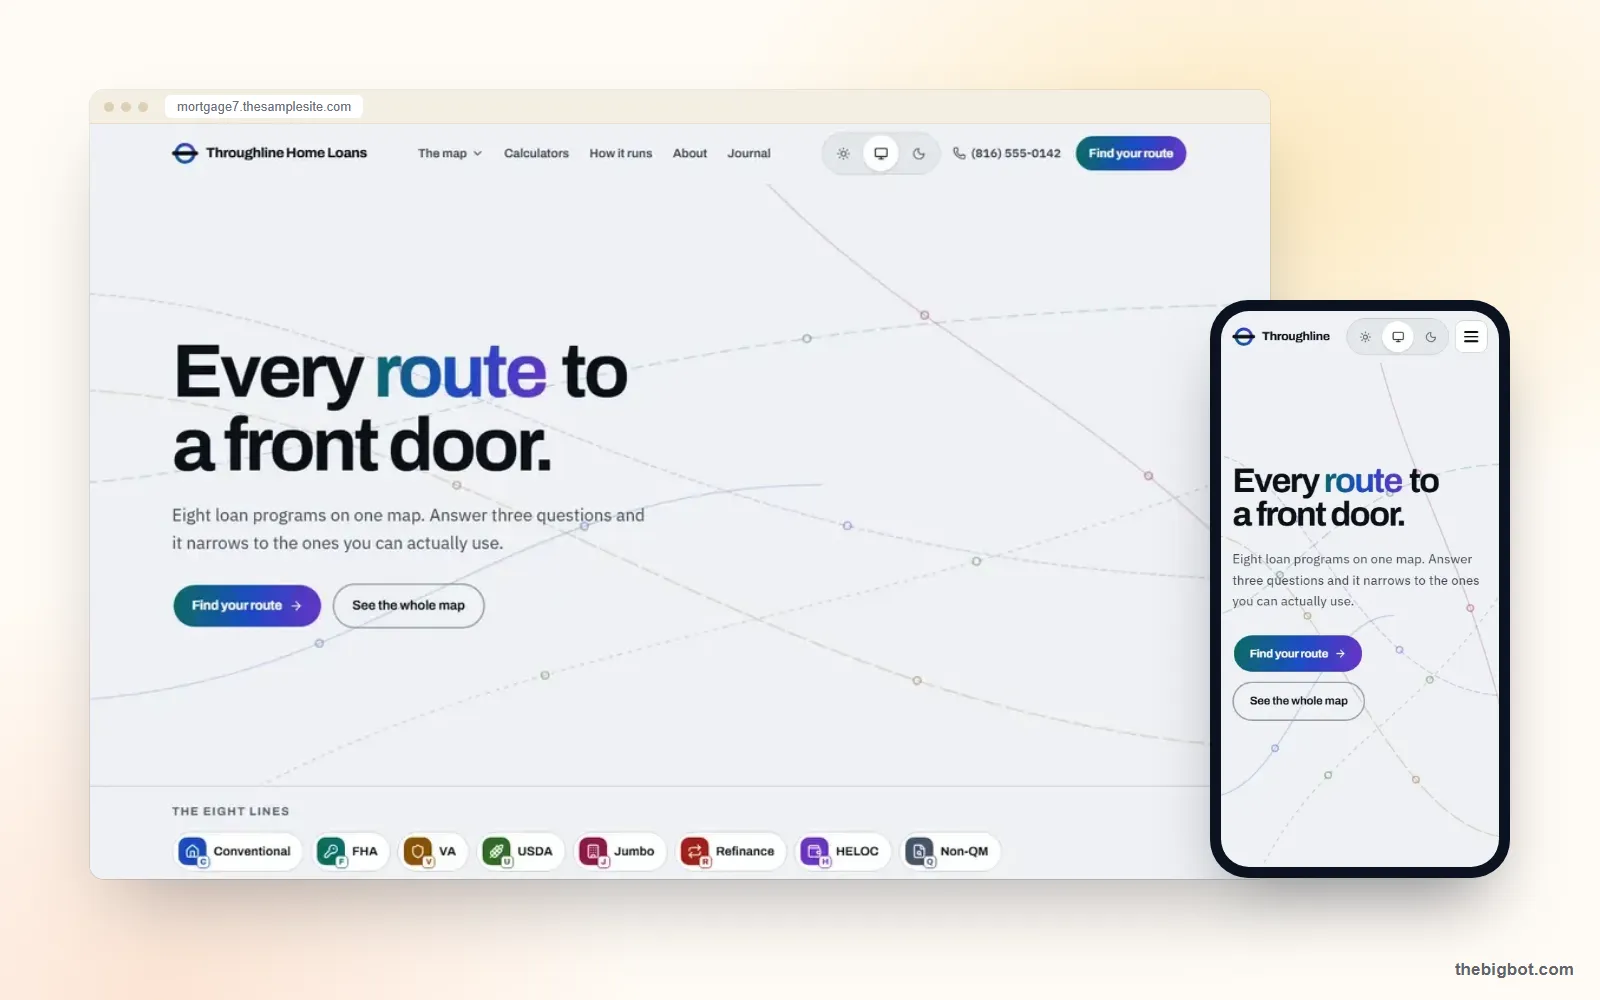
Every screen of Throughline
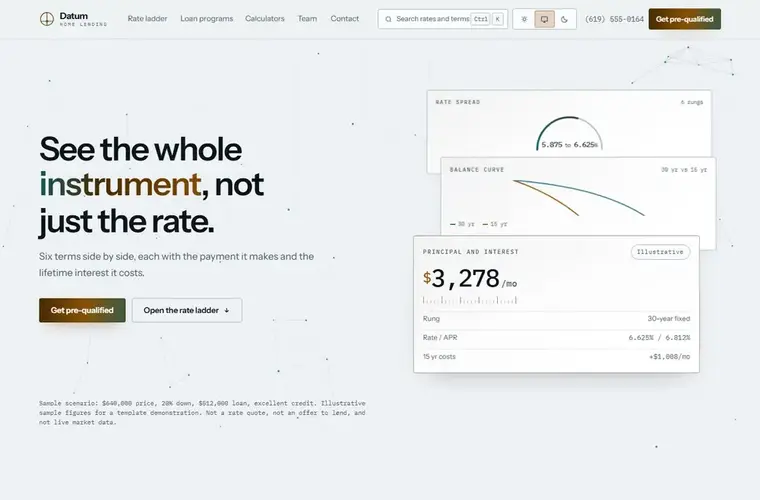
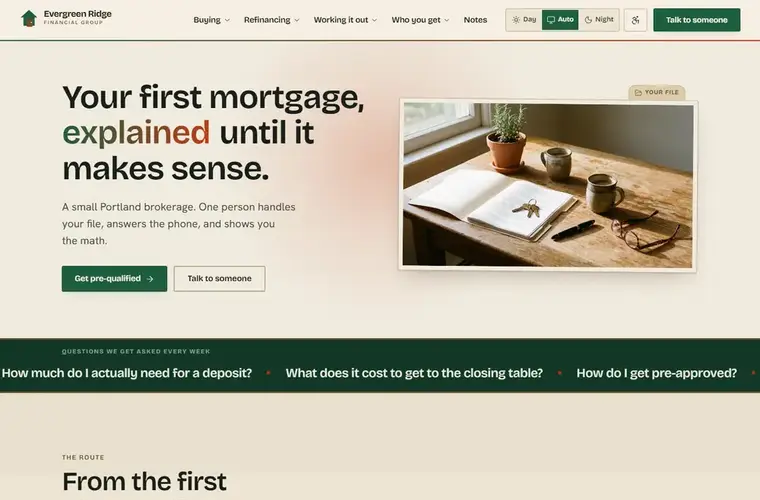
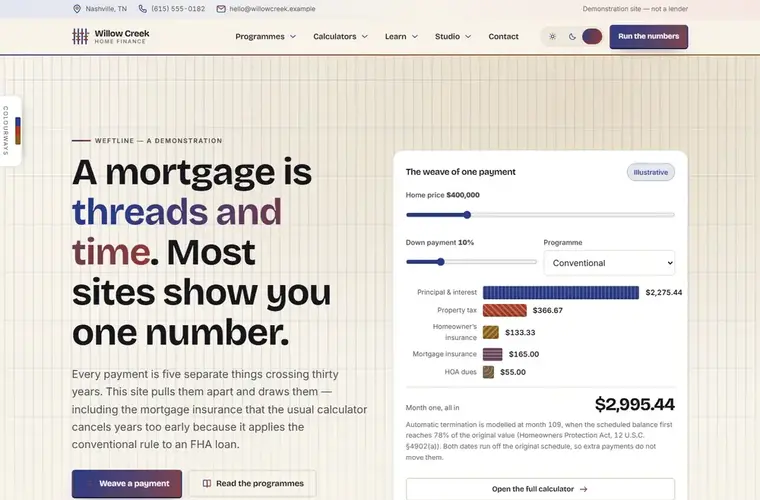
Captured from the live Throughline Home Loans demo: the program map on the home page, the loans page, the calculator, about and contact.

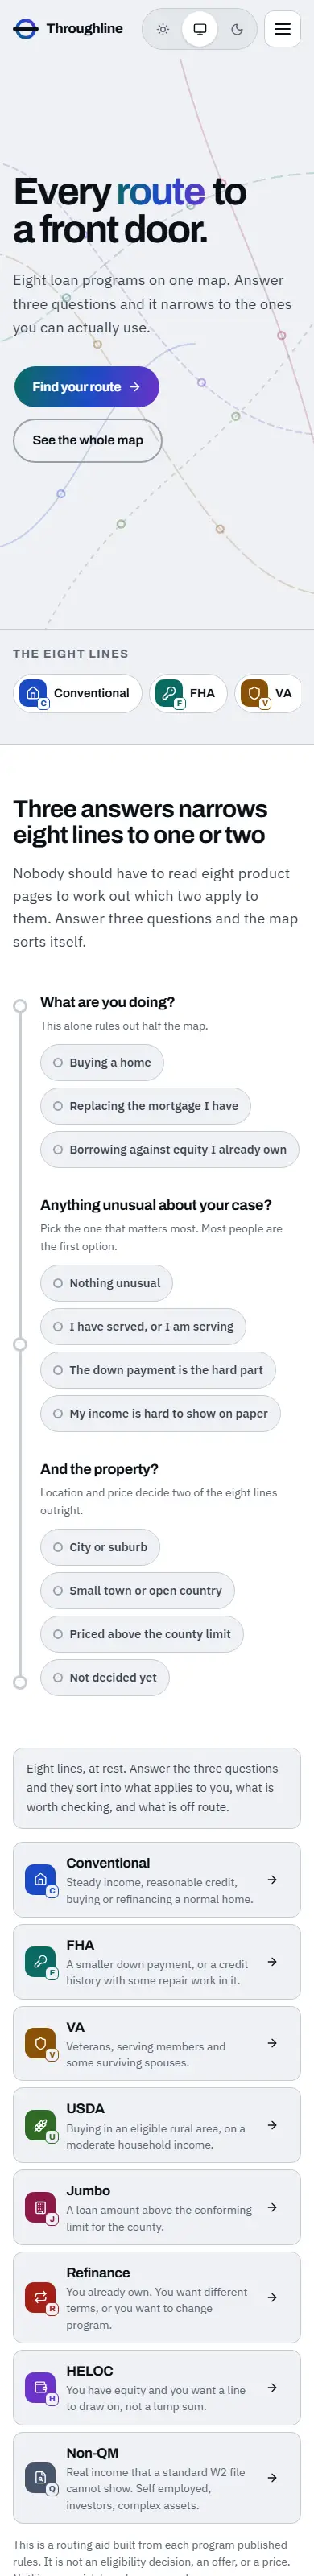


Where Throughline wins
Throughline suits a loan officer who wants a tight, fast site rather than a large library. Conventional, FHA, VA, USDA, jumbo, refinance, HELOC and non-QM sit on one map, and a short quiz points each borrower to their options.
Individual loan officers who want a focused siteOne map instead of a menu
Eight programs drawn as a single map lets a borrower see the whole landscape in one screen, which is rare and memorable.
Three questions to an answer
A short finder narrows the map to the loans a visitor can use, so the first contact is already qualified.
Twenty-four pages, all working
Small enough to keep current, which matters more than size when one person is running it.
Also on the site
Program map. All eight programs on a single visual map a borrower can follow.
Three-question finder. A short quiz that narrows the map to eligible programs.
Focused 24 pages. Map, calculators, process, about and journal without filler.
Calculator and journal. A payment calculator and a journal for your market updates.
What should a loan officer website include?
A loan officer website has two jobs: prove you are licensed and trustworthy, and turn a visitor into a booked call. The checklist covers both, and the table maps each piece to the rule or reason behind it. When we rebuild Throughline for you, each one is set up with your details.
NMLS ID and licensed states
Your NMLS number on every page, linked to your NMLS Consumer Access record, plus the states you are licensed in and any license wording those states require.
Equal Housing Opportunity
The Equal Housing Opportunity logo or statement in the footer, as fair lending advertising expects.
Compliant rate and payment wording
If you advertise a down payment, monthly payment or loan term, Regulation Z requires the APR and terms next to it. No guaranteed rates and no misleading claims under Regulation N.
A real person
Your headshot, a short bio and how long you have been originating. Borrowers pick a loan officer, not a logo.
A short first step
A pre-qualification form of a few fields with a booking calendar behind it, and a text confirmation within a minute.
Calculators and programs
A payment calculator and a plain explanation of each program you offer, so visitors arrive already knowing their options.
Real reviews
Reviews from actual borrowers, shown as written. Paying for reviews that express a particular sentiment is banned under the FTC rule on consumer reviews.
Speed and accessibility
Pages that load fast on a phone and work with a screen reader and keyboard, in line with the DOJ guidance on web accessibility.
| Element | What goes on the site | Rule or reason |
|---|---|---|
| Licensing | Your name, NMLS ID and licensed states on every page | SAFE Act licensing and unique identifier (12 U.S.C. 5103); state advertising rules |
| Online application | Your name and NMLS ID on the application form itself | Regulation Z, 12 CFR 1026.36(g) |
| Rate and payment ads | APR and terms beside any down payment, payment or term you quote | Regulation Z trigger terms, 12 CFR 1026.24 |
| Claims | No misleading statements about rates, fees or government affiliation | Regulation N, 12 CFR part 1014 |
| Fair lending | Equal Housing Opportunity logo or statement in the footer | Fair lending advertising practice |
| Reviews | Real borrower reviews, none paid for a particular sentiment | FTC rule, 16 CFR 465.4 |
| Lead capture | Short pre-qual form, booking calendar, text reply within a minute | Borrowers often contact more than one lender, so the first reply matters |
| Speed | Main content in 2.5 s, taps answered in 200 ms, layout shift under 0.1 | Google's Core Web Vitals thresholds |
| Accessibility | Readable contrast, labeled forms, keyboard navigation | DOJ guidance on the ADA and websites |
Sources: NMLS Consumer Access, SAFE Act, 12 U.S.C. 5103, Regulation Z § 1026.36 (NMLS ID on loan documents), Regulation Z § 1026.24 (advertising), Regulation N, 12 CFR part 1014, FTC rule on consumer reviews, 16 CFR 465.4, Core Web Vitals thresholds (web.dev), DOJ guidance on web accessibility.
Rebuilding Throughline as your site
Throughline is small on purpose. The rebuild keeps it at a size one loan officer can maintain without help.
- The map redrawn to your programs. Programs you do not offer leave the map, and the ones you do get your minimums and a one-line description in your words.
- The finder tuned. The three questions are adjusted so the answers only point at programs you can actually close.
- The journal handed over. The journal is set up for your market updates, with your headshot and NMLS ID on every post.
Pick Throughline if
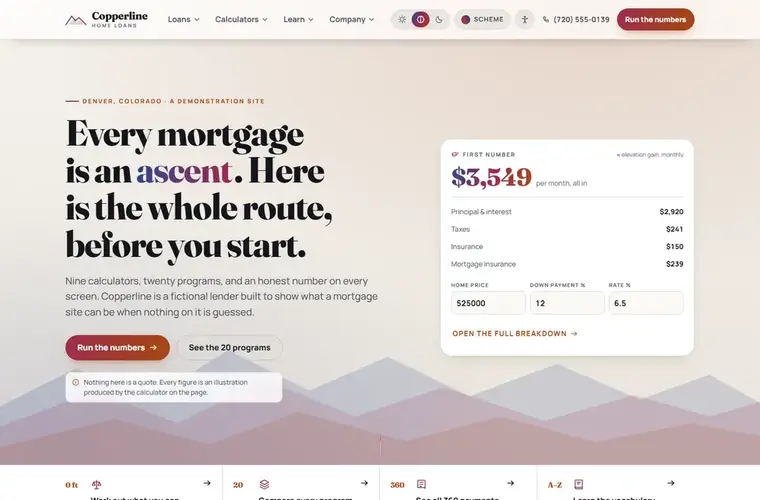
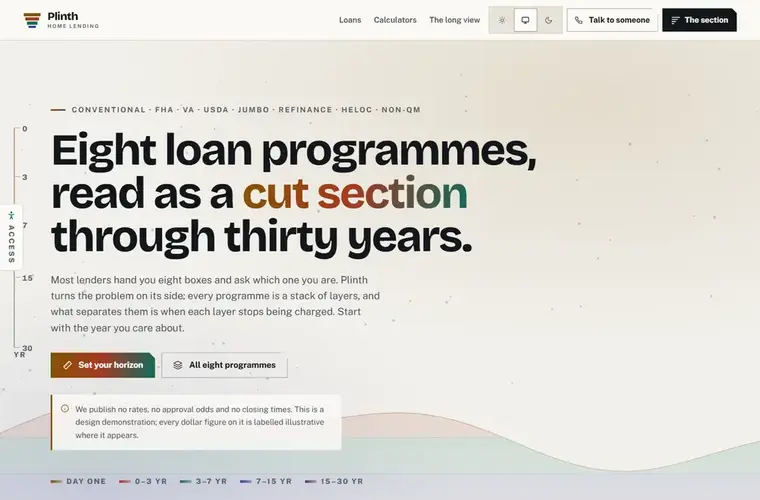
If not, Copperline or Plinth may suit you better.
- You are one loan officer and do not want a site to maintain
- Borrowers arrive unsure which program they even qualify for
- You want speed and clarity over page count
Questions about Throughline
Why is Throughline good for a single loan officer?+
Which loan programs does Throughline cover?+
What should a loan officer website include?+
How much does a loan officer website cost?+
Does a loan officer website need an NMLS ID?+
How fast should a loan officer website load?+
Where can I see loan officer website design examples?+
Launch Throughline as your website.
Eight programs on one map with your name on it, on your own domain.
Book a Demo →