
Mortgage website templateBrowse the mortgage website gallery →
Sell on total cost and stop updating rate tables
Eight programs read across day one, every month and the year the charge ends, with eleven calculators behind the argument.
- Pages
- 36
- Screens below
- 6
- Status
- Live
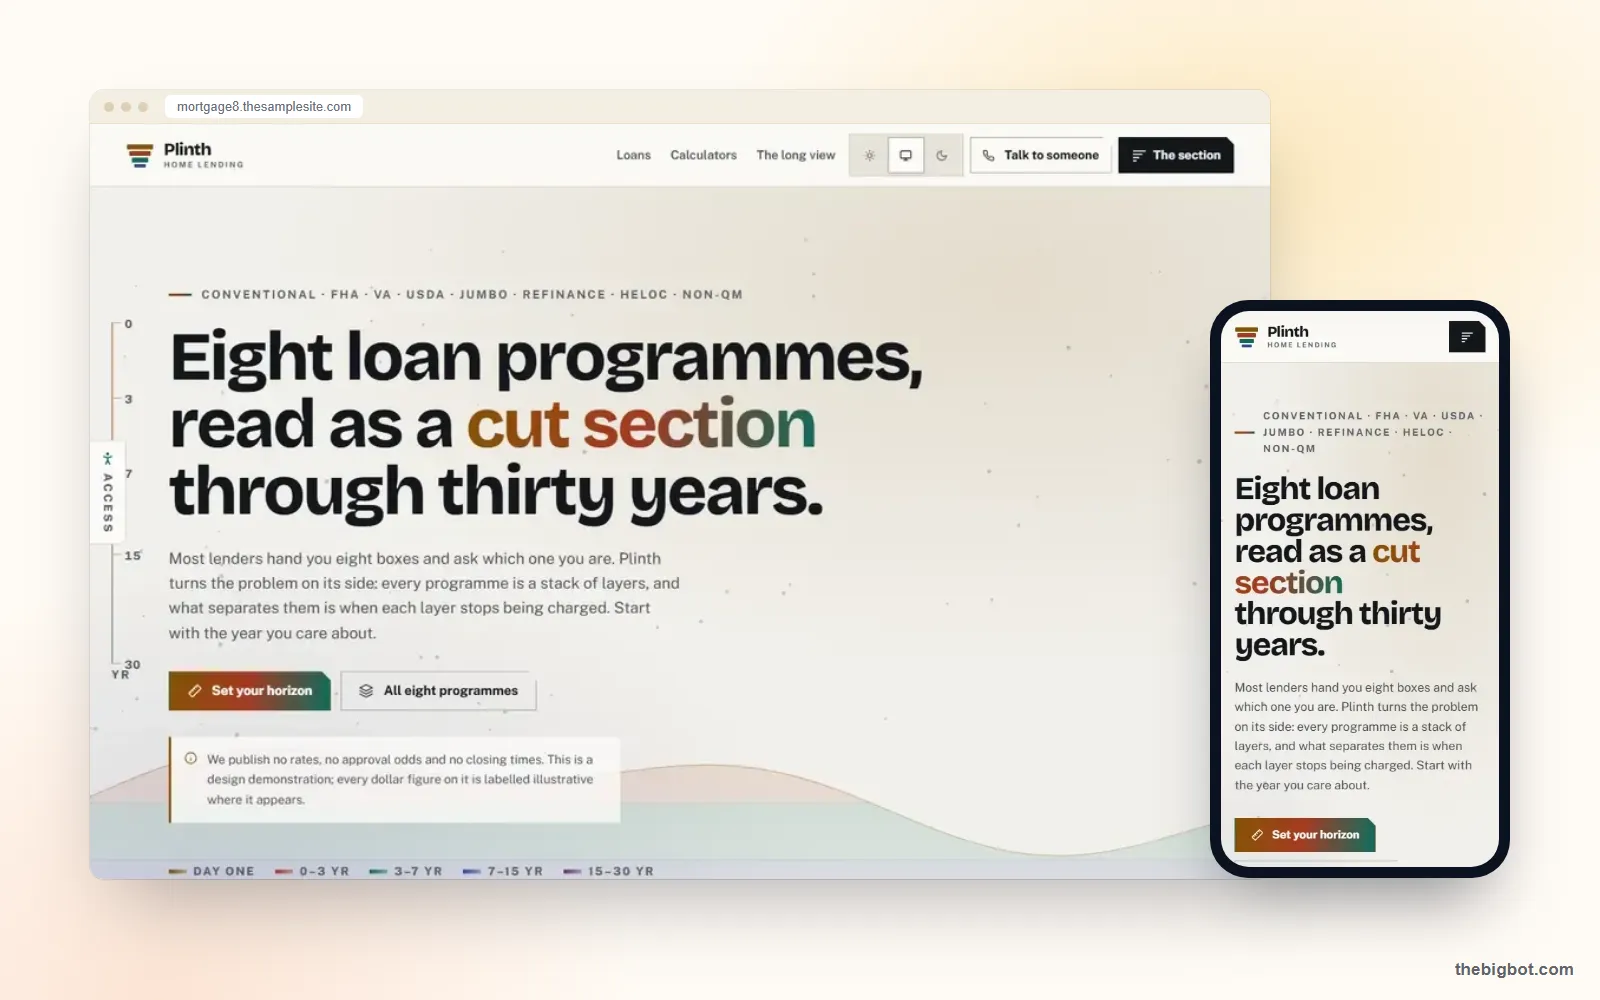
Every screen of Plinth
Captured from the live Plinth Home Lending demo: home, the loans cross-section, the calculator library, about and contact.

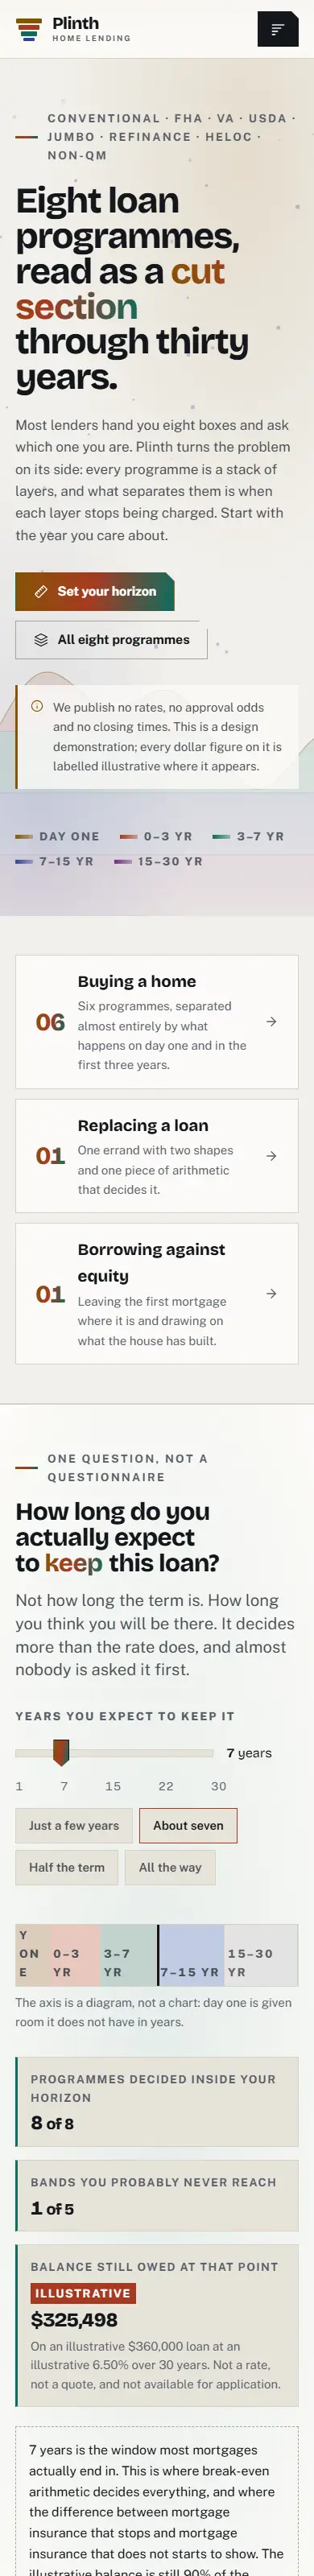


Where Plinth wins
Plinth works for a lender who wants borrowers to understand a loan across its whole life. Instead of a rate table, programs are laid out as a cross-section through thirty years, with eleven calculators behind them.
Lenders who explain cost over timePrograms ordered by time
Each loan is read across day one, every month and the year the charge ends, which is the comparison a rate table cannot make.
Eleven calculators behind the argument
Every claim on a program page has a tool that lets the visitor test it with their own numbers.
Nothing to keep updating
No rates and no ratings on the page means the content stays accurate between rate moves.
Also on the site
Cost over time. Programs compared by upfront cost, monthly cost and when charges end.
Eleven calculators. A calculator library covering payment, affordability and program comparisons.
No rate claims. The design avoids rates and ratings, which keeps pages durable.
Compact 36 pages. Loans, calculators, long-view guides, FAQ and contact.
What each loan costs on day one, every month and at the end
This is the comparison Plinth is built on. The figures below are federal program rules as of 2026; your pricing and overlays sit on top.
Conventional with PMI
Monthly private mortgage insurance until the borrower requests removal at 80% of the original value, or until it ends automatically at 78% on schedule.
FHA
An upfront premium of 1.75% plus an annual premium, 0.55% a year for most loans, paid monthly.
VA
No monthly mortgage insurance. A one-time funding fee, 2.15% on a first use with under 5% down, waived for veterans with a service-connected disability rating.
USDA
A 1% upfront guarantee fee plus 0.35% a year, for homes in eligible rural areas.
Why time decides
Which charge is cheapest depends on how long the borrower keeps the loan, which is why Plinth lays programs out across time instead of in a rate table.
Sources: Homeowners Protection Act, 12 U.S.C. 4902, HUD Mortgagee Letter 2023-05 (FHA premiums), VA funding fee, USDA guaranteed loan program.
Rebuilding Plinth as your site
Plinth sells on cost over time, so the rebuild is about getting each program’s day-one, monthly and end-of-charge figures right for your lending.
- Cost lines checked per program. Upfront fees, monthly mortgage insurance and the year each charge ends are set for every program you keep.
- Eleven calculators set to your defaults. Tax, insurance and down payment defaults reflect your market, so the long-view comparisons start from realistic numbers.
- Rate-free by design. The site stays free of rates and ratings, so nothing needs editing when the market moves.
Pick Plinth if
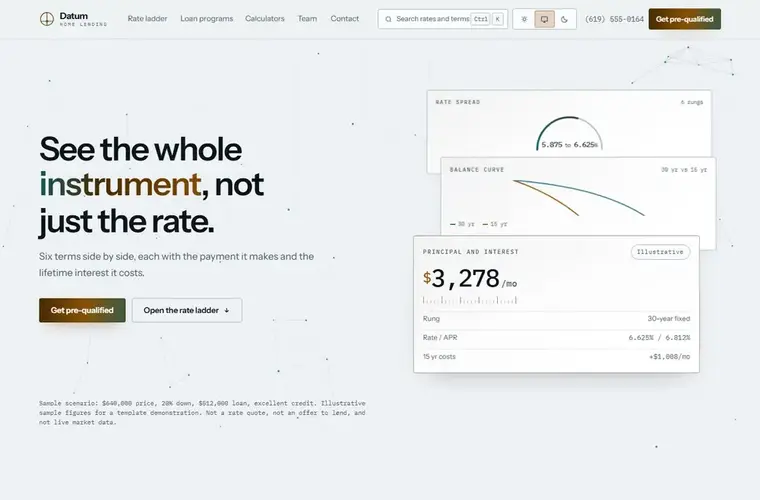
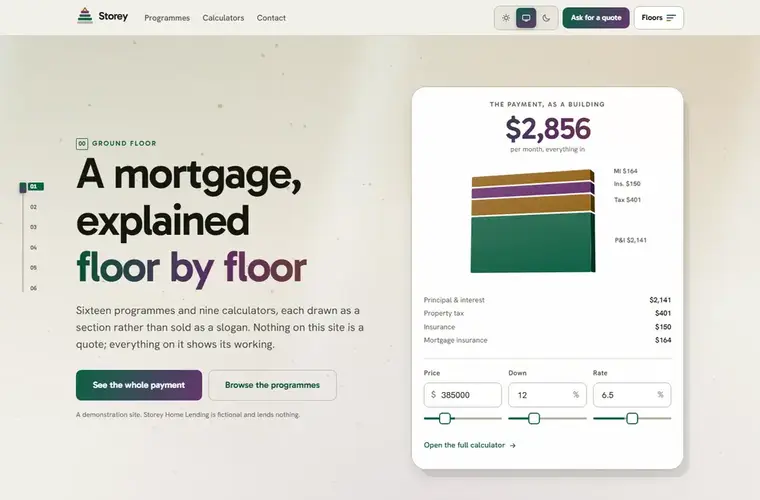
If not, Datum or Storey may suit you better.
- You sell on total cost, not on this week’s rate
- You are tired of updating rate tables that go stale
- Your borrowers compare programs, not lenders
Questions about Plinth
Is Plinth a template or a custom site?+
Why does Plinth avoid showing rates?+
Can a mortgage website template be compliant?+
How many calculators come with Plinth?+
Launch Plinth as your website.
Eight programs explained across thirty years, rebranded on your own domain.
Book a Demo →