⚡ Done-for-you growth — we run GoHighLevel & your social so you don't have to · No contract
Book a Demo →

First-time homebuyer mortgage websiteMortgage broker website design gallery →

First-time buyers who already understand the loan

Plain-English guides to every route to a first set of keys, so your calls start at "when can we apply" instead of "what is PMI".

Pages
77
Screens below
6
Status
Live
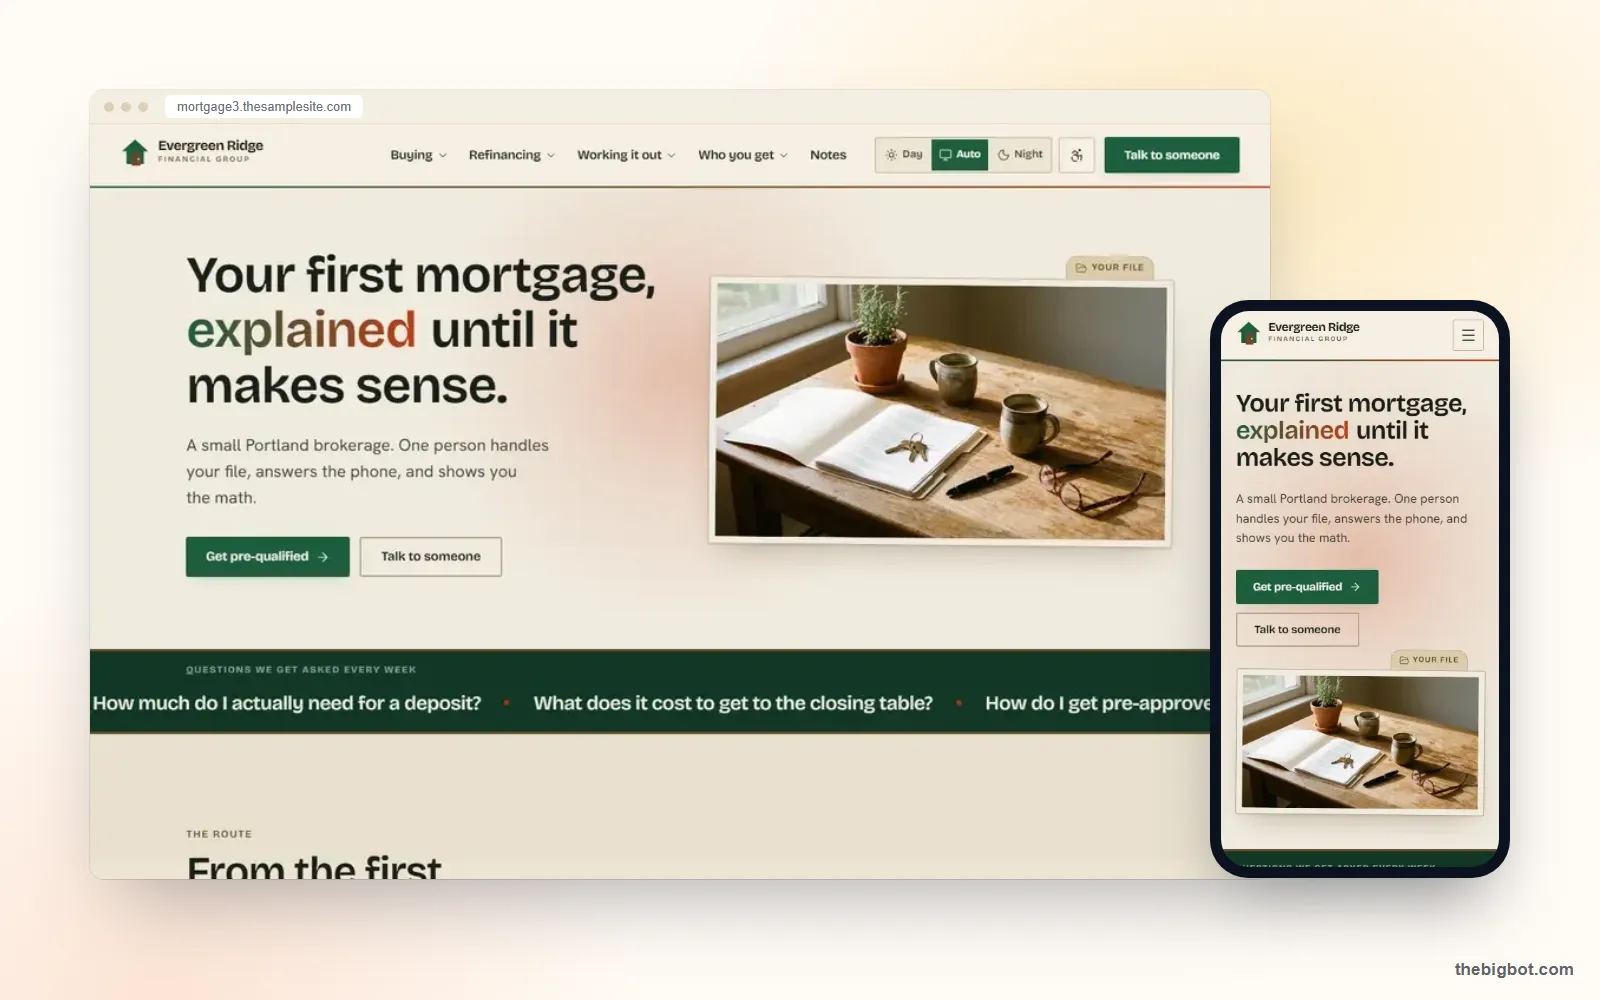
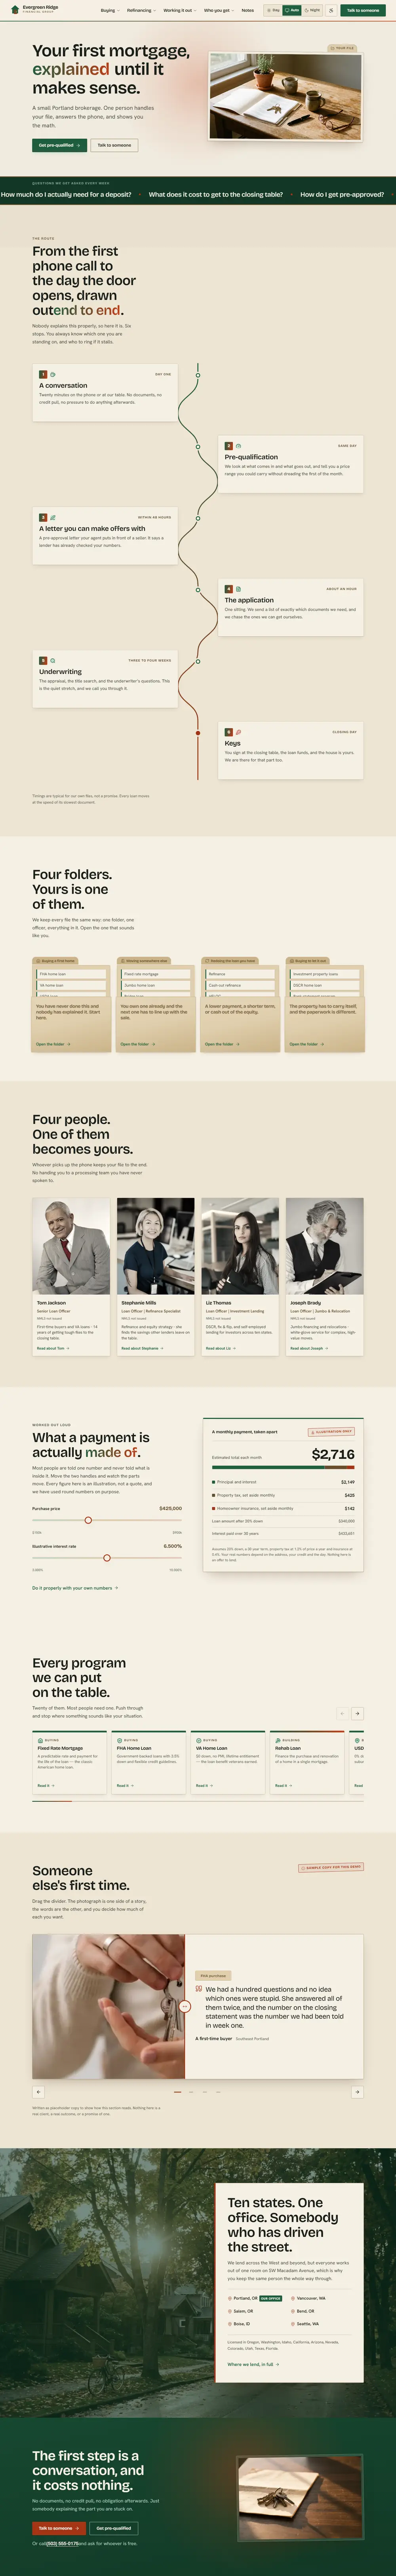
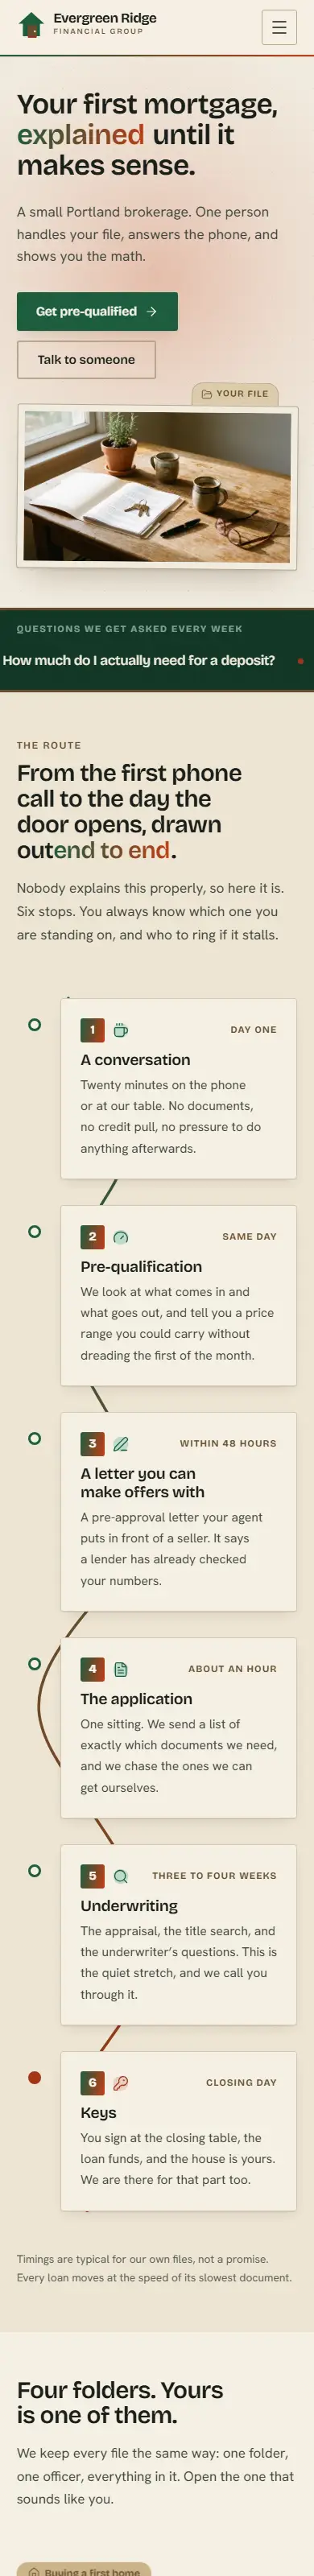
Evergreen Ridge mortgage website design shown on a desktop browser and a phone

Every screen of Evergreen Ridge

Captured from the live Evergreen Ridge Financial Group demo: the start-here home page, the loan options explainers, the learning center and the about page with the team.

Where Evergreen Ridge wins

Evergreen Ridge is written for a small brokerage whose borrowers are buying for the first time. The navigation starts with buying, refinancing and working it out, and every loan type is explained before it is sold.

Brokerages that specialize in first-time buyers

Plain words before products

Every loan type is explained in a sentence a first-time buyer can repeat to their partner, which is what gets forwarded and linked to.

A start-here path

The navigation opens with buying, refinancing and working it out, so a nervous visitor is never asked to choose a product they cannot name yet.

A named person on the file

Team pages promise one loan officer per file, which is the differentiator small brokerages actually win on.

Also on the site

Start-here guidance. A first-time buyer path that explains terms before asking for an application.

Program explainers. FHA, VA, USDA, low down payment and jumbo pages written in plain words.

One loan officer per file. Team pages that show borrowers exactly who will handle their loan.

Day and night reading modes. Light, dark and device-following themes for comfortable long reads.

The five programs a first-time buyer site has to explain

Most first-time buyers assume they need 20% down. These are the routes that say otherwise, and the questions your site should answer before the first call. Figures are program rules as of 2026; your rate sheet and overlays decide the rest.

FHA

3.5% minimum down

Mortgage insurance
1.75% upfront plus 0.55% a year for most loans
Who qualifies
Credit score of 580 or higher for 3.5% down. Open to repeat buyers too.

Conventional 97

3% minimum down

Mortgage insurance
Private mortgage insurance, removable once you reach 20% equity
Who qualifies
At least one borrower must be a first-time buyer. No income limit.

HomeReady / Home Possible

3% minimum down

Mortgage insurance
Reduced private mortgage insurance coverage
Who qualifies
Income at or below 80% of the area median. Homebuyer education required.

VA

0% minimum down

Mortgage insurance
No monthly mortgage insurance. One-time 2.15% funding fee on a first use with under 5% down
Who qualifies
Eligible veterans, service members and some surviving spouses. Fee waived with a service-connected disability rating.

USDA

0% minimum down

Mortgage insurance
1% upfront guarantee fee plus 0.35% a year
Who qualifies
Home in an eligible rural area and household income at or below 115% of the area median.

Sources: HUD Mortgagee Letter 2023-05 (FHA premiums), Fannie Mae 97% LTV options, VA funding fee, USDA guaranteed loan program.

Rebuilding Evergreen Ridge as your site

Evergreen Ridge is written for people who have never bought a home, so the rebuild keeps that plain voice and swaps in your programs and your people.

Behind the formsQuestions from the start-here path land in the mortgage CRM, the buyer gets a text and email within 60 seconds, and evening calls reach the AI receptionist for loan officers, which books a consult.
  1. Programs matched to your lending. The FHA, VA, USDA, Conventional 97 and HomeReady explainers are kept for the programs you offer and rewritten with your credit and down payment minimums.
  2. Your loan officers on the file. The one-loan-officer-per-file team pages are rebuilt with your people, headshots and NMLS numbers.
  3. Calculators set for first-time budgets. Default down payment, mortgage insurance and tax figures are set so a 3% or 3.5% down scenario shows the full monthly cost.

Pick Evergreen Ridge if

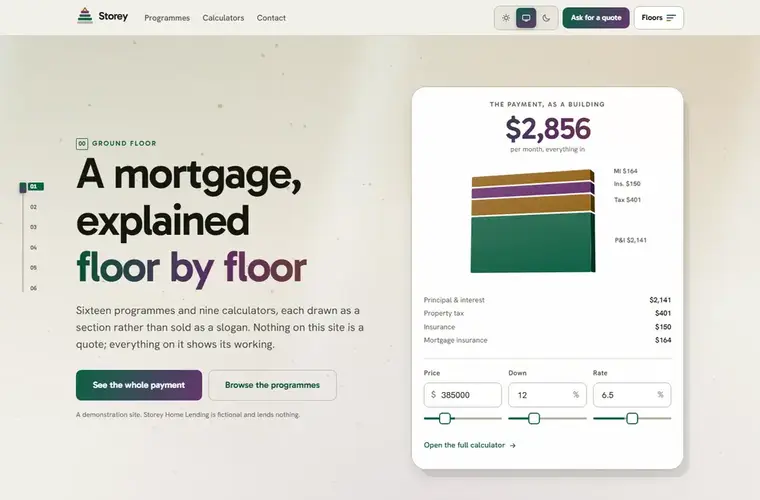
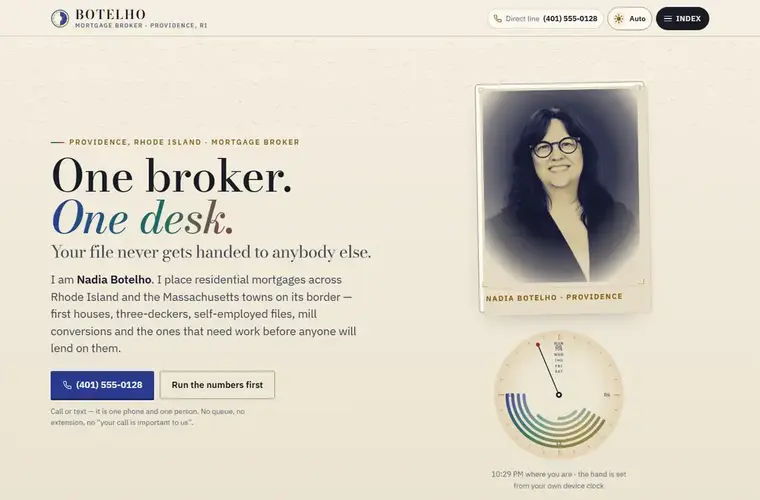
If not, Storey or Botelho may suit you better.

  • Most of your pipeline is buying for the first time
  • You spend calls explaining what FHA, PMI and escrow actually mean
  • You want to be the lender who explained it, not the one who quoted fastest

Questions about Evergreen Ridge

Why is Evergreen Ridge good for first-time buyers?
+
It explains each loan type in plain language, starts visitors on a first-time buyer path and keeps calculators and guides one click away.
Can Evergreen Ridge include my team?
+
Yes. The team pages are rebuilt with your loan officers, photos and NMLS numbers.
Which loan programs should a first-time buyer mortgage website explain?
+
At minimum FHA, VA, USDA, Conventional 97 and HomeReady or Home Possible. Those five cover the low and no down payment routes most first-time buyers ask about, from 3.5% down on FHA to 0% down on VA and USDA.
Do first-time buyers need 20% down?
+
No. Conventional 97 and HomeReady allow 3% down, FHA allows 3.5% with a 580 credit score, and VA and USDA allow 0% down for eligible borrowers. Putting less than 20% down usually means paying mortgage insurance or a guarantee fee.

Launch Evergreen Ridge as your website.

Plain-English guides with your programs and your loan officers, on your own domain.

Book a Demo →