
Commercial mortgage broker websiteMortgage broker website design gallery →
Speak the language sponsors use before they call
Eight commercial programs sized on DSCR, debt yield and LTV, from multifamily to ground-up construction.
- Pages
- 38
- Screens below
- 6
- Status
- Live
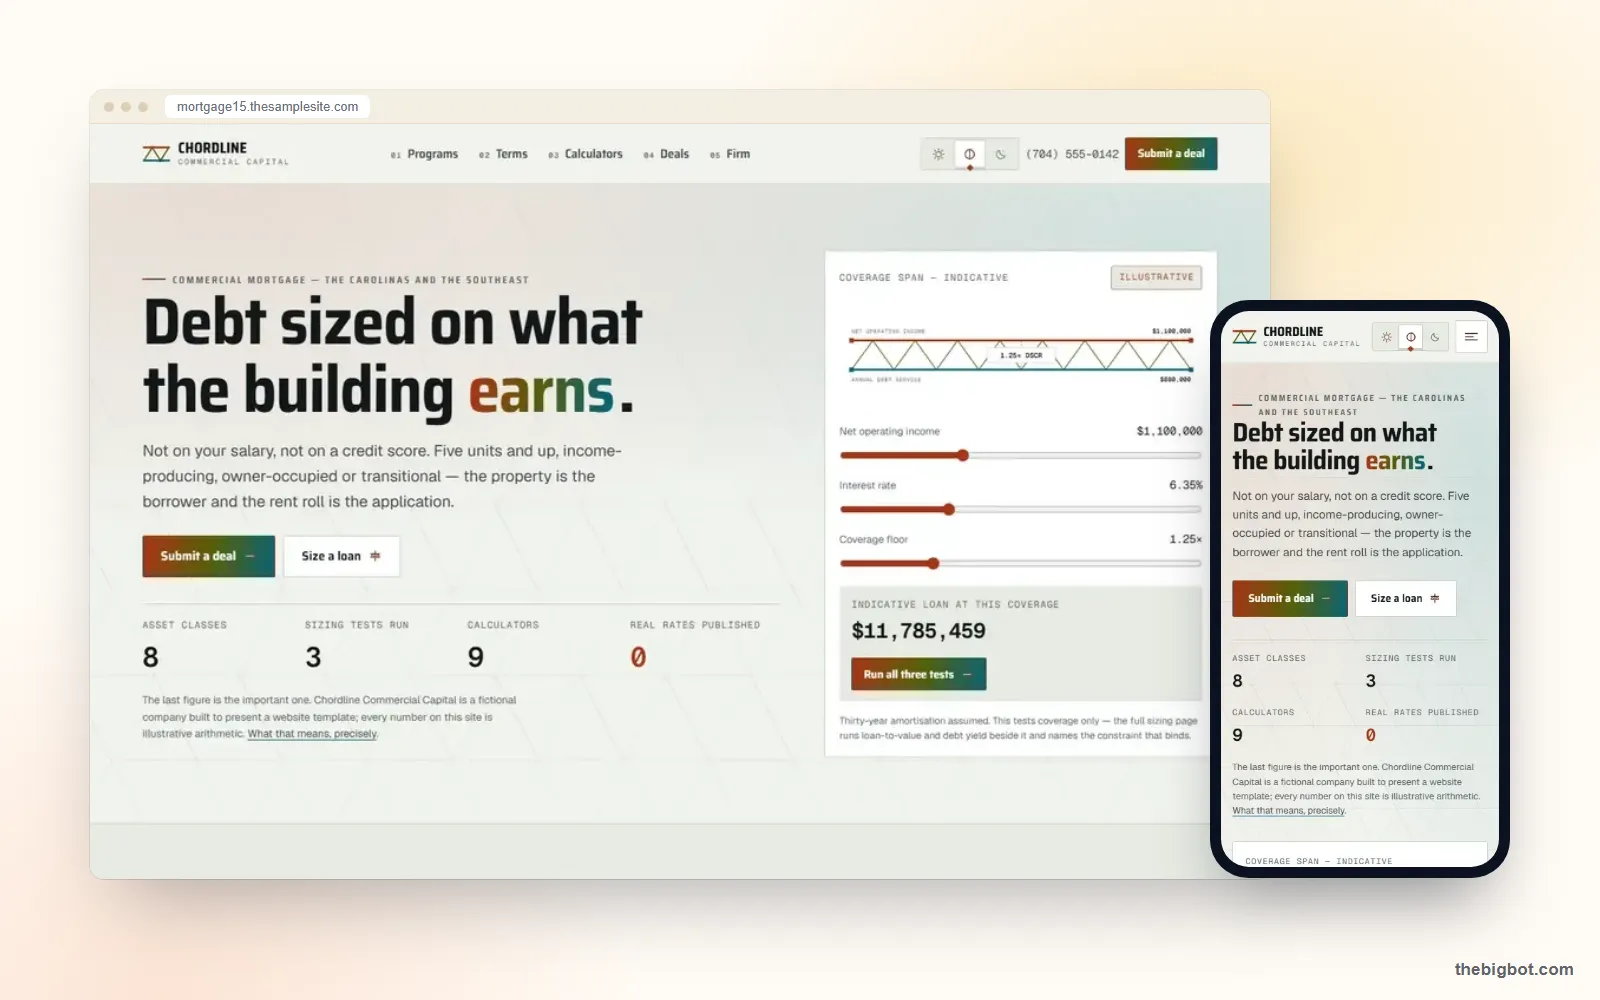
Every screen of Chordline
Captured from the live Chordline Commercial Capital demo: home, the programs index, the commercial calculators, about and contact.

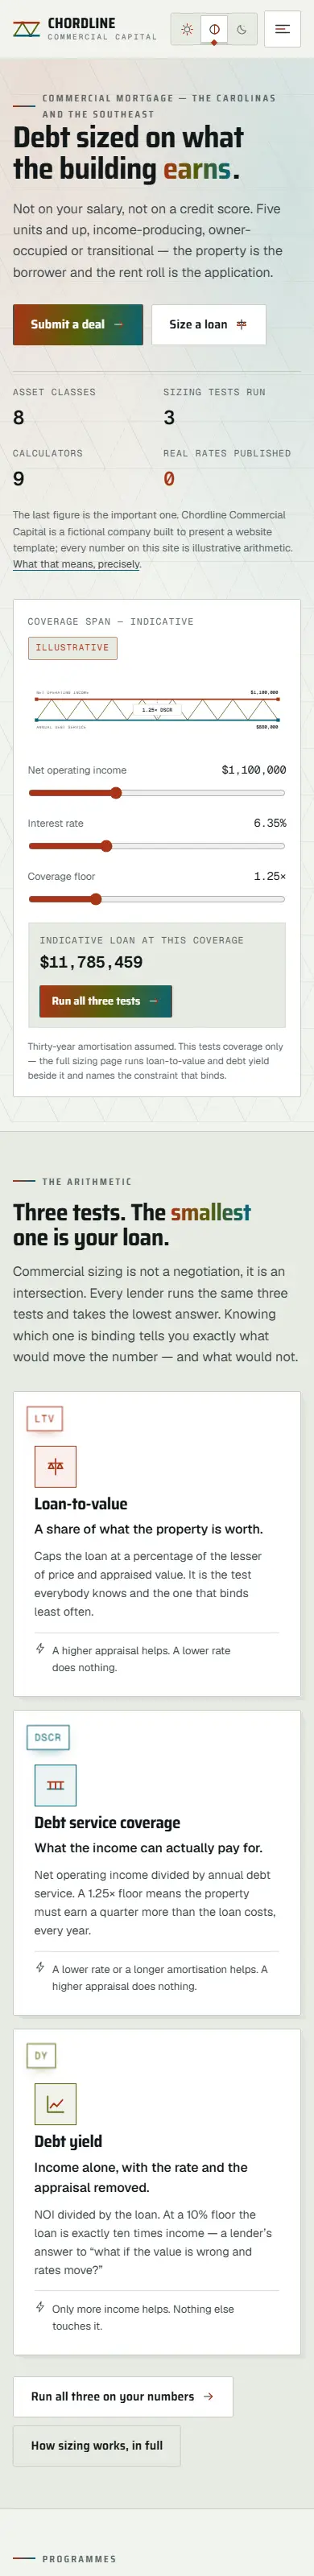


Where Chordline wins
Chordline is built for commercial real estate finance. It suits a broker or lender placing debt on income-producing property, with program pages for multifamily, retail, industrial, office, bridge, construction, SBA and specialty assets.
Commercial mortgage brokers and lendersSizing explained before pricing
LTV, DSCR and debt yield are laid out as the way a loan is built, which is the language a sponsor uses.
Eight asset types, eight pages
Multifamily, retail, industrial, office, bridge, construction, SBA and specialty each get their own page and their own searches.
Commercial calculators, not consumer ones
The tools model the deal rather than a household budget, so the site reads as built by someone who does this.
Also on the site
Eight commercial programs. Multifamily, retail, industrial, office, bridge, construction, SBA and specialty.
Sizing explained. How LTV, DSCR and debt yield decide the loan amount.
Commercial calculators. Tools built for income property, not home buyers.
Deal-focused 38 pages. Programs, terms, calculators, insights and FAQ.
How a commercial loan gets sized
Commercial borrowers are qualified on the property, not the paycheck. These are the three tests Chordline explains, and the loan is the largest amount that passes all of them.
Loan-to-value
Loan amount divided by the appraised value of the property. It caps how much of the value the lender will finance.
Debt service coverage ratio
Net operating income divided by annual debt service. It shows whether the property’s income covers the loan payments with room to spare.
Debt yield
Net operating income divided by the loan amount. It ignores rate and amortization, which is why lenders use it as a check when rates move.
The test that binds
Each test produces a maximum loan, and the lowest of the three wins. A sponsor who sees all three can work out which one limits the deal before calling.
Rebuilding Chordline as your site
Chordline speaks to sponsors and investors, so the rebuild centers on the asset types and loan sizes you actually place.
- Programs matched to your capital sources. The eight asset-type pages keep the property types you place, with your typical loan size range and terms.
- Sizing language set to your box. The LTV, DSCR and debt yield pages state the ranges your capital sources work within, labeled as typical rather than guaranteed.
- Insights for your market. The insights section is set up for your deal notes and market commentary.
Pick Chordline if
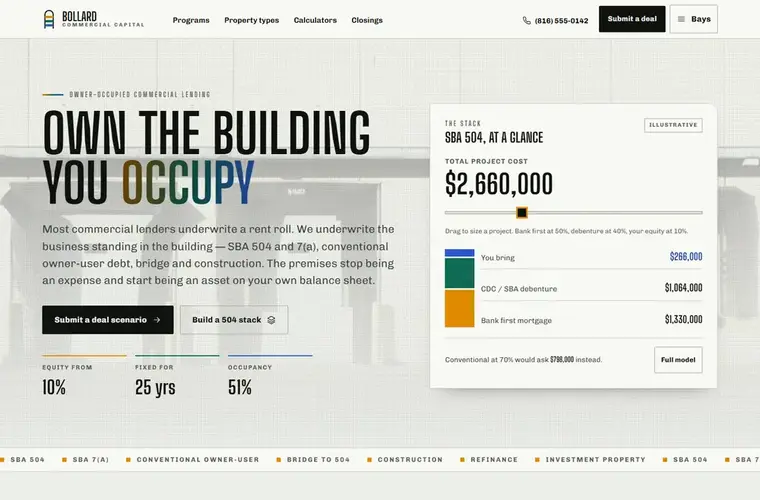
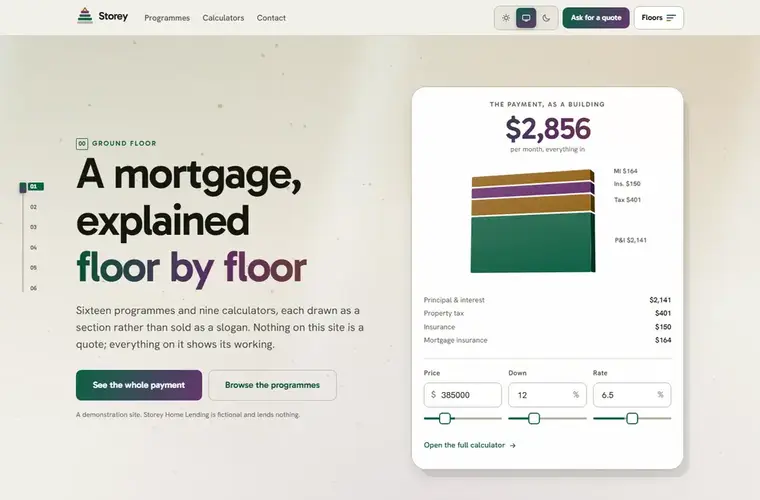
If not, Bollard or Storey may suit you better.
- You place debt on income-producing property
- Your borrowers ask how a loan gets sized, not what the rate is
- You want multifamily, retail, industrial and office as separate pages
Questions about Chordline
Is Chordline suitable for a commercial mortgage broker?+
Does Chordline explain DSCR and debt yield?+
What should a commercial mortgage broker website include?+
Does Chordline cover bridge and construction loans?+
Launch Chordline as your website.
Eight commercial programs under your name, on your own domain.
Book a Demo →