
Non-QM mortgage broker websiteMortgage website examples for loan officers →
Win the self-employed files your competitors decline
Bank statement, P&L, asset depletion and DSCR loans explained, with a calculator that turns deposits into qualifying income.
- Pages
- 32
- Screens below
- 6
- Status
- Live
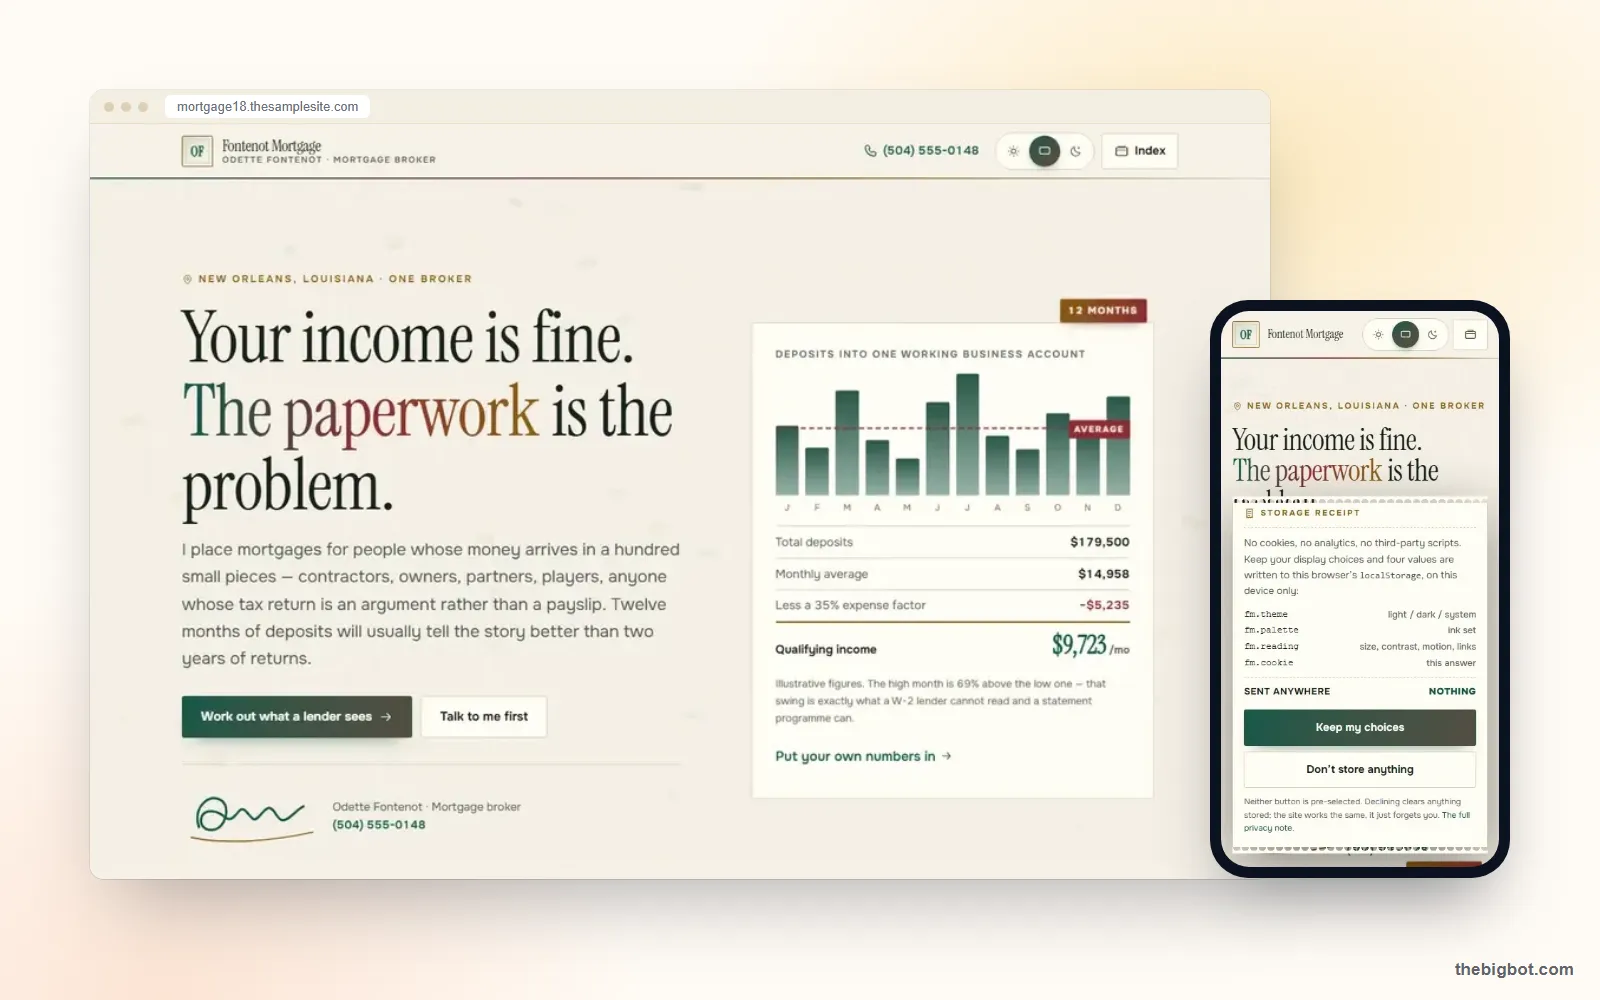
Every screen of Fontenot
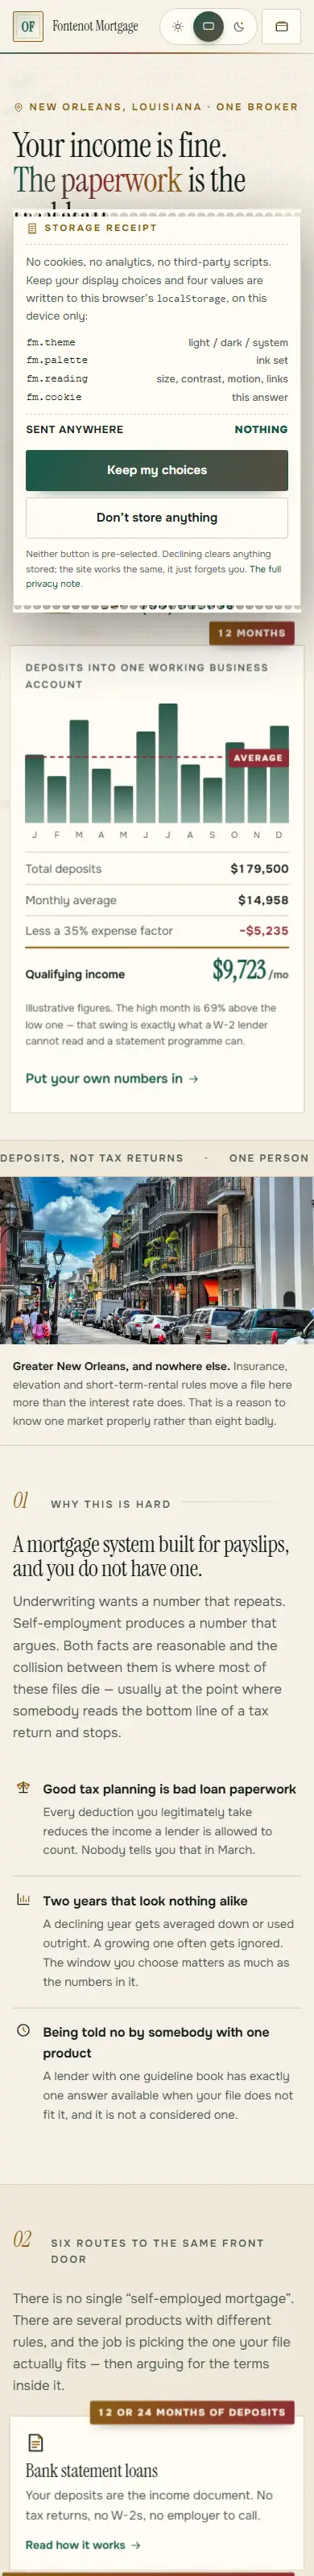
Captured from the live Fontenot Mortgage demo: the broker-led home page, services, the calculators including self-employed income, about and contact.



Where Fontenot wins
Fontenot suits a broker who specializes in non-QM lending. It speaks directly to self-employed borrowers and investors, explains how each alternative documentation loan works and includes a self-employed income calculator.
Non-QM brokersIt names the real problem
The site opens with the income being fine and the paperwork being the problem, which is exactly how a self-employed borrower describes it.
Alternative documentation, page by page
Bank statement, P&L, asset depletion and DSCR each get a page, so each search finds a page written for it.
A way out of a bridge loan
A refinance page for borrowers leaving hard money captures a search almost nobody else writes for.
Also on the site
Non-QM loan pages. Bank statement, P&L, asset depletion and DSCR investment loans.
Eight calculators. Including self-employed income, DSCR and affordability.
Refinance out of hard money. A page for borrowers leaving a bridge loan.
Broker-led voice. A named broker with direct contact on every page.
How non-QM loans qualify a borrower
Non-QM loans are not no-doc loans. They use different documents to prove the same thing, and these are the routes Fontenot explains.
Bank statement loans
Income is calculated from 12 or 24 months of deposits, with an expense factor taken off business accounts.
P&L loans
A profit and loss statement, usually prepared or signed by a CPA or tax preparer, stands in for tax returns.
Asset depletion
Liquid assets are divided over a set number of months to create a qualifying income.
DSCR investor loans
The property qualifies instead of the borrower: monthly rent divided by the full housing payment. Many programs look for a ratio of 1.0 or higher.
Ability to repay still applies
Federal rules still require a good-faith determination, based on verified information, that the borrower can repay.
Rebuilding Fontenot as your site
Fontenot is written for borrowers who have been declined elsewhere, so the rebuild keeps that directness and fits it to the non-QM programs you place.
- Programs matched to your investors. The bank statement, P&L, asset depletion and DSCR pages keep the programs you can place, with your typical minimums.
- Income calculator tuned. The self-employed income calculator uses the expense factors and statement periods your lenders apply.
- Hard-money exit page kept. The refinance-out-of-bridge page is rewritten for the exit products you offer.
Pick Fontenot if
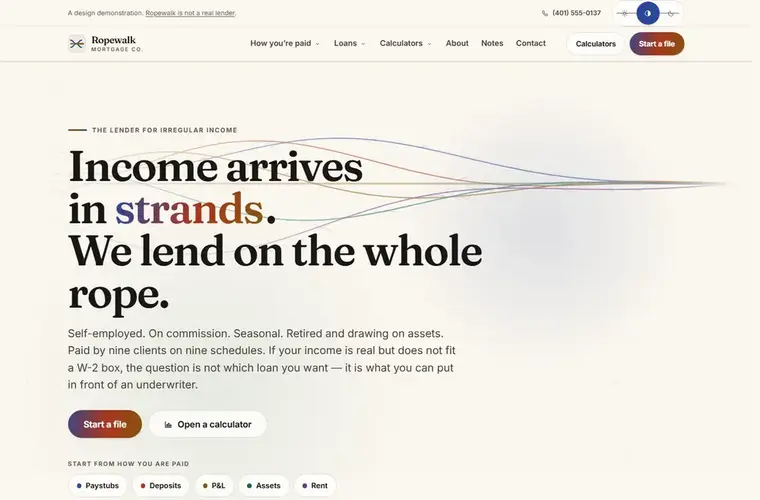
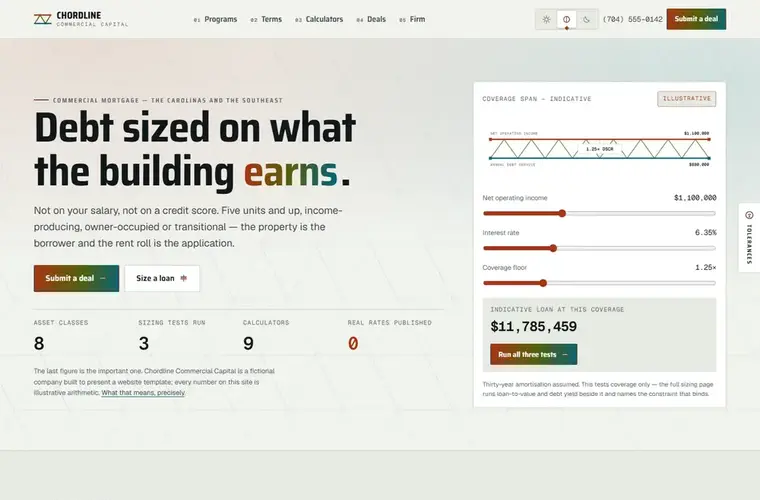
If not, Ropewalk or Chordline may suit you better.
- Bank statement, P&L, asset depletion and DSCR are your business
- Your borrowers have been declined somewhere with a W-2 checklist
- You want a calculator that turns deposits into qualifying income
Questions about Fontenot
How is Fontenot different from Ropewalk?+
Does Fontenot include a DSCR calculator?+
What is a non-QM mortgage?+
Who is a non-QM broker website for?+
Launch Fontenot as your website.
Non-QM programs explained in your voice, on your own domain.
Book a Demo →